GRANDSPLAINING...It's as Bad as it Sounds!

We need more respectful inter-generational communication

Jun 24, 2026

8 min

Sue Pimento

Summary:   "Grandsplaining" is a playful term that captures the all-too-familiar situation where younger generations offer unsolicited advice to older family members, often in a manner that is as condescending as it is unhelpful. This behaviour can be perceived as disrespectful and potentially creates awkward communication barriers, emotional strain, and family tension. Rooted in ageist stereotypes, it can even undermine elders' self-esteem. Here, we explore alternatives to grandsplaining, including the radical concepts of genuinely listening, asking open-ended questions, demonstrating empathy, and avoiding assumptions. These suggestions aim to help adult children support their older family members—not merely swoop in with a "fix-it" attitude.


The Disrespectful Impact of Condescending Advice on Seniors


When I helped older Canadians navigate financing their retirements, I often witnessed what can only be described as "grandsplaining in the wild." Conversations between adult children and their elders usually felt less like dialogues and more like lectures—one-sided advice sessions that left everyone gritting their teeth.


The younger relative, likely well-meaning, would offer suggestions like, “You should downsize and buy a condo,” “Sell and rent,” or, the pièce de resistance, “Move in with family!” Judging by the withering looks from their elders, it was clear this approach wasn’t winning any "Favorite Child" awards.


The older family members often felt patronized, as though their decades of life experience had been conveniently forgotten. The advice was condescending, painfully obvious, and usually impractical or unwanted. The dynamic reminded me of the cringeworthy experience of being "mansplained." And that’s when it hit me: this is “grandsplaining.”


Unfortunately, grandsplaining can turn retirement planning conversations into a crash course on how not to communicate! Fortunately, with a little effort (and much less lecturing), families can turn this ship around and build stronger, more respectful relationships.


What is "Grandsplaining"?


In an age where communication flows freely across digital platforms, I define "grandsplaining" as a colloquial expression to describe a situation where younger generations offer unsolicited advice to older individuals, often patronizing or condescendingly.


Grandsplaining typically involves a younger person explaining something to an older individual in a way that belittles their experience or intelligence. The term combines "grand" (suggesting age or status) and "splaining" (a slang term for condescendingly explaining something). While the intention behind such advice may often be well-meaning, the delivery can be patronizing, reinforcing stereotypes about aging and competence.


This behaviour can significantly undermine the dignity and autonomy of seniors, leading to feelings of frustration, resentment, and a sense of being marginalized. Understanding the nuances of grandsplaining sheds light on intergenerational dynamics in these conversations. We must find a better, more respectful, and effective way to communicate with our elders considering retiring.


The phenomenon of grandsplaining can manifest in various contexts, not just financing retirement—whether it’s discussing technology, lifestyle choices, healthcare options, or even social norms. For instance, a grandchild might explain how to use a smartphone app to a grandparent, assuming that the older generation cannot understand it despite their own lifelong experience with technology in different forms.


Communication Breakdown


In an era where financial literacy and retirement planning are more crucial than ever, "grandsplaining" has become a significant barrier to effective communication between generations.


Retirees often feel overwhelmed or dismissed when their relatives provide unsolicited advice, especially if it contradicts their wants or financial strategies. This can lead to a reluctance to engage in discussions about finances, creating a rift that undermines the potential for collaborative planning. When adult children dominate conversations with preconceived notions of financial management, it stifles the opportunity for seniors to express their feelings, share their knowledge, and collaborate on effective retirement strategies.


The Generation Gap in Financial Understanding


Adult children may rely on outdated financial paradigms that no longer apply to their elders' realities. The economic landscape has changed dramatically over the past few decades, with shifts in real estate markets, a lack of formal retirement plans, and longer life expectancies. This generational gap can lead to misguided advice that does not consider modern challenges such as retiring with debt, little or no pension income, or rising living costs.


Emotional Strain and Family Tension


When relatives impose their views, it can evoke frustration, resentment, or inadequacy in their elders. This dynamic can shift the conversation from one focused on financial empowerment to one steeped in emotional conflict and shame. Instead of fostering a supportive environment for discussing retirement goals, grandsplaining can create adversarial relationships where seniors feel belittled or pressured, further complicating an already sensitive topic.


Erosion of Autonomy


When relatives try to impose their methods or strategies, it can undermine the seniors’ independence, making them feel a lack of control over their finances. Financial decisions are deeply personal and often intertwined with individual circumstances, goals, and values. This loss of agency not only affects financial outcomes but can also impact the mental well-being of older adults, leading to feelings of incompetence or anxiety about their financial futures.


The Context of Ageism


The implications of ageism are particularly concerning in a rapidly changing world characterized by technological advancements and unprecedented changes in social norms. While younger generations may genuinely wish to assist their elders in navigating these changes, their actions can reinforce negative stereotypes rather than empower seniors. Grandsplaining highlights the generational divide, creating an "us versus them" mentality that hinders collaboration and mutual understanding.


Grandsplaining is deeply intertwined with ageism, a pervasive societal attitude that discriminates against individuals based on their age. Ageism manifests in various forms, including stereotypes that depict older adults as technologically inept, resistant to change, or incapable of learning. These stereotypes can lead to the marginalization of seniors within families and communities. Not cool!


When younger generations adopt a condescending tone, they inadvertently reinforce ageist stereotypes that portray older adults as out of touch or incapable. This affects individual relationships and perpetuates societal narratives devaluing older individuals' contributions and wisdom.


The Impact on Relationships


Grandsplaining can strain relationships between generations, fostering resentment and conflict. For many seniors, unsolicited advice can infringe on their autonomy, making them feel infantilized or disrespected.


I've seen firsthand how parents can react defensively to younger family members and sometimes withdraw altogether from conversations. When assistance is delivered condescendingly, it can backfire. The resulting tension may prevent meaningful conversations about important topics, such as healthcare decisions or lifestyle changes, which are crucial for seniors' well-being.


The Psychological Impact on Seniors


Being on the receiving end of condescending advice can also lead to diminished self-esteem and increased feelings of inadequacy. Seniors may begin to internalize the belief that they are not capable of making sound decisions or understanding new concepts, which can further exacerbate issues related to aging, such as cognitive decline and depression. 


Encouraging Respectful Communication with Seniors


Addressing the issue of grandsplaining requires a concerted effort from both younger and older generations to cultivate respectful communication. Here are several strategies to foster more positive intergenerational interactions:


1. Actively Listen: Younger people should prioritize active listening when engaging with seniors. This involves hearing what the older person says and validating their experiences and perspectives. Younger people can create a more respectful dialogue by acknowledging their knowledge and expertise.


2. Seek to Understand: Younger generations must approach conversations with empathy. To quote Stephen Covey's wise words, "Seek first to understand, then to be understood."  Recognizing seniors' challenges, such as health issues or technological gaps, can foster a sense of compassion. This approach can help bridge the generational divide and promote more constructive conversations.


3. Avoid Assumptions: The tendency to assume that older adults are out of touch or incapable can lead to grandsplaining. Instead, younger individuals should avoid making assumptions about seniors’ knowledge or abilities. Asking questions like “What do you think about this?” or “How do you feel about that?” can empower seniors to share their insights and experiences.


4. Offer Support, Not Solutions: Ask questions like, “What does a successful retirement look like to you? How do you plan to finance your retirement? Do you want to stay in this home? Are you open to moving? If so, where? Do you have enough in savings? How can I support you in having an independent and dignified retirement”?


5. Understand the Bigger Picture: Don’t assume that the traditional strategies of downsizing, selling, renting, or moving in with family are reasonable solutions for your elder in today’s economic environment. These retirement strategies are problematic for today’s seniors. In most cases, downsizing only works financially if the retiree is willing to move to a smaller, more affordable community. Most seniors want to stay in their communities and not move away from family, friends, churches, or familiar shops and services. Selling, renting, or moving in with family requires the sale of their significant appreciating asset. Given today's longer life expectancies, it's not always a wise choice.


6. Humour:    By skillfully using humour, you can turn potentially patronizing situations into moments of connection and shared joy, ensuring that conversations with elders remain meaningful, respectful and memorable. For example, you could start the conversation this way; "The last thing I want to do is give you advice. That would be ridiculous. You’re the wise sensei here—I’m just the clueless apprentice trying to save enough downpayment to buy a shoebox of a house." This approach humorously flips the script, poking fun at the presumptuousness of unsolicited advice while emphasizing the elder's experience and wisdom.


People often feel judged or vulnerable when discussing finances or significant life changes. Humour shifts the dynamic, showing that you approach the conversation as an ally, not an adversary. For example: "Talking about budgets isn’t fun for anyone—I mean, who loves math? But it’s worth it if we can figure out how to turn this retirement conversation into Canada Day rather than Labour Day!" This playful approach lowers barriers, making the discussion feel collaborative rather than critical.


Laughter fosters connection. Sharing a laugh creates a sense of camaraderie, making it easier for people to open up about sensitive topics. When elders feel that you’re not judging them but partnering with them—and can make them smile—they’re far more likely to trust your intentions and take your advice seriously. Humour invites the other person to join the conversation, breaking the ice and encouraging them to share their thoughts. It sets a tone that the conversation is a dialogue, not a lecture. Example: "You’ve been making great financial decisions for decades. I’m here to ensure we don’t accidentally end up with a basement full of K-tel Veg-O-Matics… unless that’s the plan?" This allows them to laugh, respond, and engage while respecting their autonomy.


A word of caution.  Humour is only effective when paired with genuine respect and sensitivity. Pay attention to your elder's reactions and adapt if they seem uncomfortable or unamused. The goal is to build rapport, not to win laughs at their expense. Using humour skillfully, you can turn potentially patronizing situations into moments of connection and shared joy, ensuring that conversations with elders are respectful and memorable.


Before You Go


Good financial planning thrives on clear communication, but grandsplaining tends to turn productive discussions into monologues that undermine elder autonomy and trigger emotional static. To create a more harmonious environment, families should swap their megaphones for listening ears and embrace a collaborative approach that respects seniors' wisdom and frames younger relatives’ financial theories as conversation starters, not TED Talks.


After all, when it comes to navigating retirement planning, a little less "know-it-all" and a bit more "let’s figure it out together" can go a long way. Think of it as building a bridge, not a lecture podium—because nothing says "family unity" like tackling compound interest together!


Don’t Retire…Re-Wire!


Sue


My Book is Now Available for Pre-Order

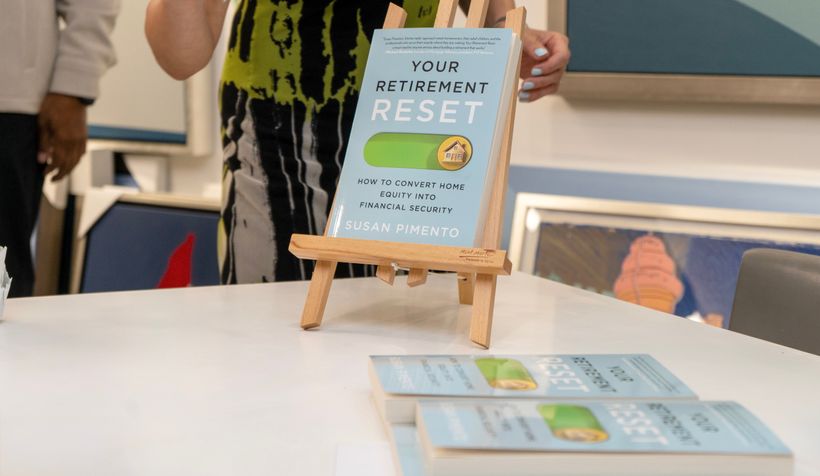
I hope you will consider pre-ordering a copy of Your Retirement Reset for you, a friend or loved one. It's available September 8, 2026 published by ECW Press - You can now order at Indigo or Amazon. And if you love supporting Canadian booksellers, please also check with your local independent bookstore. Most can easily order it for you.
Connect with:
Sue Pimento

Sue Pimento

Founder | CEO

Writer, author & presenter focused on financial literacy and retirement strategies. I advocate for the health, wealth & purpose for retirees

Pension ReformInterest RatesHome EquityMortgagesReverse Mortgages
Powered by

You might also like...

Check out some other posts from Retire with Equity

MEDIA ADVISORY: “Your Retirement Reset” by Canadian Retirement Expert Susan Pimento Arrives in Bookstores Across Canada featured image

3 min

MEDIA ADVISORY: “Your Retirement Reset” by Canadian Retirement Expert Susan Pimento Arrives in Bookstores Across Canada

Practical guide to turning home equity into lasting retirement income is now available at Indigo, independent bookstores, Amazon.ca and McNally Robinson, and through Simon & Schuster in the U.S., in paperback, ebook and audiobook. Pimento is on a national media tour. TORONTO, ONTARIO, CANADA, September 29, 2026 -- Many Canadians share the same quiet worry: running out of money before they run out of life. Retirement expert Susan Pimento has a name for it: FORO, the Fear Of Running Out. As of today, her answer to it is in bookstores across the country. Your Retirement Reset: How to Convert Home Equity into Financial Security, published by ECW Press, is now in stores nationwide, including Indigo and Chapters locations and independent booksellers. It is also available on Amazon.ca and from Canadian independent bookseller McNally Robinson, in trade paperback, ebook and audiobook. In the United States, readers can order the book through Simon & Schuster. The book is written for Canadians in or near retirement and for the adult children who help them plan. It addresses a gap in how Canadians talk about retirement. Most advice is about saving. Very little explains how to turn what people have built into steady income that lasts. For many retirees, the family home is their largest asset. Your Retirement Reset explains, in plain language, the tools Canadians can use to unlock home equity. It shows how those tools fit alongside government benefits and registered savings, and how to weigh the trade-offs with family before making a decision. “Canadians have been told to save, save, save. Nobody tells them how to spend it,” said Pimento. “Meanwhile, the biggest asset most retirees own is right under their feet, and they’ve been taught to treat it like it’s off limits. A lot of people are house-rich and cheque-poor. This book is for anyone lying awake at 3 a.m. doing retirement math. You’ve done the hard part. Now let’s make it work for you.” “The book is about something that affects every one of us. How we're going to live and live well in the second half of our lives. Sue challenges us to think differently about retirement, especially the difference between having assets and having the income we need to enjoy life. She also challenges the traditional idea that the equity in our homes should simply sit there untouched until we die. Used thoughtfully and conservatively, she believes home equity can be a part of the retirement income conversation,” said Jennifer Smith, Publisher at ECW Press, at the book launch. National Media Tour Underway Susan Pimento is on a national media tour, and ECW Press is booking interviews with broadcast, print, podcast and online outlets. She can speak to: FORO (the Fear Of Running Out) and why it is keeping retirees up at night How Canadians can use home equity safely as a source of retirement income Common myths about reverse mortgages and downsizing What the shift from defined benefit to defined contribution pensions means for today’s retirees How adult children can start the money conversation with their parents To request an interview, contact Cassie Smyth, Publicist, at ECW Press (details below). Readers can find free resources and learn more about Pimento’s work at retirewithequity.ca. Book Details Title: Your Retirement Reset: How to Convert Home Equity into Financial Security Author: Susan Pimento Publisher: ECW Press In stores: September 29, 2026 Formats: Trade paperback, ebook, audiobook Price: $28.95 (Canada); US$28.95 (United States) ISBN (paperback): 978-1-77041-897-4 Pages: 280 US distribution: Simon & Schuster About Susan Pimento and Retire with Equity Susan Pimento is a Canadian retirement expert, author and founder of Retire with Equity, an education and advocacy platform on retirement financing. She spent more than 30 years in banking and mortgage lending, including as a Vice President at a Schedule I bank. She advises financial institutions and policymakers on modernizing retirement solutions for Canadians 55+, and co-authored EY Canada’s report The Canadian Retirement Evolution. Her motto: “Don’t Retire…ReWire!” Learn more at retirewithequity.ca Media Contact Cassie Smyth, Publicist ECW Press cassie@ecwpress.com | 416-694-3348 | info@ecwpress.com

The Algebra of Writing a Book featured image

9 min

The Algebra of Writing a Book

As I stood there before friends, family, colleagues, and the people who had actually agreed to come celebrate a book I wrote, I found myself thinking about how all of this had become possible. There it was my name on the cover. A real book. Something that had started as a vague idea, survived several versions, considerable self-doubt, and a few grammatical interventions, and somehow made it into the world. People frequently ask me about the process. How did you write a book? Where did the idea come from? How did you actually get it finished? The honest answer is that I didn't really know what I was doing. I just kept going long enough to figure some things out. So, in honour of the launch, I thought I would share the formula. I call it The Algebra of Writing a Book. A quick disclaimer before we begin. This is a personal formula, based on a sample size of one, occasionally supervised by a patient editor and a ten-pound she-dog named Dottie, who treats every writing session as a personal invitation to stop working and pay attention. It has not been peer-reviewed by an actual mathematician, unless being an MBA student now qualifies me to turn every human experience into an equation, whether it wants to cooperate or not. The inspiration came partly from Scott Galloway, whose The Algebra of Happiness and The Algebra of Wealth take complicated subjects and distil them into memorable formulas (Galloway, 2019, 2024). What I admired was not the formula at the end of each chapter. It was the discipline behind it. He takes a messy human subject, studies it long enough to understand the mechanics, and then gives readers something they can actually use. For years, I have spent at least a couple of hours a day reading or listening to people who think more clearly than I do. I don't just want to know what they think. I want to understand how they got there. How did they make that point? Why did that sentence work? What did they leave out? Where did they slow down? A surprising number of the ideas I now think of as my own started somewhere else. I turn them over, pull them apart, mix them with my own experience, and, if I'm lucky, they come back sounding like me. I think of them as my thought babies: borrowed genetics, raised in my household until they develop a personality. Research + Experience + Curiosity = Original Ideas At least, that was the theory. Then life decided to test it. At 65, I lost my job. Financially, I was fine. Thirty years in financial services had taken care of that. Emotionally, however, I discovered I had built a surprisingly large part of my identity on a business card. Take away the title, the office, the meetings, the responsibilities and the people who needed you to make decisions, and suddenly you are left wondering who exactly you are supposed to be on Tuesday morning. Naturally, I responded in the most emotionally healthy way I could think of. I built a business case for my reinvention. There was a timeline. There were measurable deliverables. There may even have been a Gantt chart. Picture it: a newly unemployed woman trying to project-manage her emotional recovery as though grief were a product launch. Phase One: Feel Better. Phase Two: Discover New Purpose. Phase Three: Become Inspiring. It was a spectacular failure. A few weeks later, I was sitting in my car in a grocery store parking lot with the engine off, unwilling to go inside and buy milk like someone who actually had somewhere to be. My beautifully organized recovery plan had collapsed somewhere around Phase One. It turns out grief has very little respect for bullet points. What I needed was permission to be a mess for a while. So I gave myself one small instruction: write something five days a week. Not something good. Not something publishable. Not something anyone besides Dottie and I would ever read. Just something. I did not commit to writing a book. I committed to trying. I gave myself permission to be terrible at it for as long as it took. That turned out to be the important part. Somewhere in all that low-stakes trying, I fell in love with writing. I became fascinated by how a good writer can take an idea you’ve been carrying around vaguely for years and suddenly put exactly the right words around it. You read the sentence and think, yes. That's it. That's exactly what I've been trying to say. Stealing Homework David Brooks once described writers as “beggars who tell other beggars where they found bread.” He used the phrase in a 2023 Persuasion interview with Yascha Mounk, calling it one of his favourite sayings about writing (Mounk, 2023). I loved it because it gave me permission to stop pretending that every good idea had originated in my own head. I started paying attention not only to what good writers said but also to how they built an argument, why certain words carried more weight, and how a simple metaphor could sometimes accomplish what three pages of explanation could not. I carried a notebook everywhere. I wrote down phrases that stopped me. I noticed metaphors the way other people notice good haircuts. Patricia O'Conner's Woe Is I: The Grammarphobe's Guide to Better English in Plain English quietly repaired decades of my grammatical freelancing as I tried to figure out why six words could sometimes explain something better than six paragraphs. Then came Christine. Two years and three complete versions of the manuscript later, I had something that vaguely resembled a book. That was largely thanks to Christine, a PhD, teacher, and four-time published author, who agreed to help a woman whose writing experience began and ended with mortgage disclosure statements. Christine was smart, generous, and wonderfully direct. She was also a regular in my GoodLife Fitness classes, which meant she had already watched me botch choreography in public before she read a word of my writing. I had very little dignity left to protect. Her first editorial assessment was concise: “Sue, your grammar sucks.” Fair enough. Her second question was why I insisted on capitalizing the word Mortgage as though it deserved the same reverence as God or Beyoncé. I still don’t have a good answer. But Christine's most important contribution had nothing to do with grammar. My manuscript was full of financial information and professional jargon. It was smart enough, but it wasn't human enough. Buried inside it was Clara, a character representing the ordinary people I had spent my career trying to help. The truth was that I had trouble accessing the human side of aging, finance and retirement. It was much easier to talk about the process and the products than to be vulnerable about what I had actually gone through. Christine kept pushing me. Tell the human story. Go deeper. Be more vulnerable. Stop hiding behind your expertise. She was right. Slowly, Clara became more real. As Clara became more real, so did I. Somewhere along the way, I stopped being an author trying to protect my professional credibility and became a woman willing to be seen. That changed the book. It also changed me. It helped me heal some of the wounds I hadn't realized I was carrying. And somewhere in the middle of all that editing, Christine and I became better friends. I didn't want to disappoint her, which turned out to be a far better motivator than any deadline. Finishing the manuscript didn’t feel like a triumph. It felt more like handing someone something soft and unfinished, hoping they wouldn’t drop it. As long as the book was unfinished, I had an excellent excuse: “I’m working on a book.” Very impressive. Very aspirational. Very safe. Once it was finished, there was nowhere left to hide. So I hired an agent and let him absorb the rejection on my behalf. He sent the manuscript out. Three responses came back. One publisher said, “Thanks, but no thanks.” Two said yes. Suddenly, a woman with three decades in mortgage lending, a character named Clara, and an unapologetic attachment to writing was going to be an author. Which brings me to the actual algebra. Curiosity + Permission to Fail + Consistent Effort + Time = A Finished Manuscript Notice what is missing. There is no talent requirement. No inspiration variable. No line item for knowing what you're doing before you start. There is simply a small, repeatable behaviour applied without judging the results too harshly. And here is the part I especially want to emphasize: I was 65 when I lost my job, and 70 when my book was published. Five years. Is five years too long to reinvent yourself? I doubt it. We have somehow convinced ourselves that reinvention should happen quickly, preferably between lunch and the afternoon news. But some things take time. Five years gave me time to learn, write badly, rewrite, improve, find my voice, work with Christine, survive rejection, heal old wounds, and eventually become an author. Five years earlier, I would never have put “write a book” on my list of things to do. At 65, I was trying to figure out who I was without the job that had defined so much of my adult life. At 70, I was standing in front of friends and family, holding a published book with my name on it. Here is the link to the the launch party interview if you have 37 minutes (or 24 minutes at 1.5x).  We spend a lot of time planning for retirement as though we are planning a trip. We think about where we will live, how much money we will need, and what we will do with our time. All important questions. But life doesn't always follow the itinerary. Sometimes the thing you think is the ending turns out to be the beginning of the next chapter. My other formula became: Loss + Curiosity + Permission + Action + Time = Reinvention My two background mantras throughout all of this were simple: It is never too late. If not now, when? They sound almost embarrassingly obvious, but obvious does not mean easy. I have watched too many people postpone the things they want to do until some imaginary future when they will have more time, more confidence, more energy, or fewer obligations. There is always a reason to wait. I had plenty of them myself. You cannot get to “one day” without committing to “day one.” For me, day one wasn't about writing a book. It was about writing one thing. Then another. Then another. Five days out of seven. Eventually, those small acts of showing up became a manuscript. The manuscript became a book. And five years after losing my job, at 70, that book became real. And I became a better human. Scott Galloway gave me the idea of looking for the algebra beneath a complicated subject. David Brooks gave me permission to admit that writers borrow, learn from, and build on one another. Christine gave me the courage to stop hiding behind my expertise and to let the human story into the book. Dottie gave me a very reliable reason to stop writing and go for a walk. And a 65-year-old woman who had just lost a huge part of her identity gave herself permission to be bad at something new. Five days out of seven. For long enough. Apparently, that was enough. Today, Your Retirement Reset is out in the world, on bookshelves, in libraries, and with readers across Canada. More than sixty blog posts have grown out of the same process, a considerably better showing than that Gantt chart ever managed. If there is something on the back burner that you keep telling yourself you will do someday, don't start with the big plan. Try something small. Give yourself permission to be terrible. Then show up again. Make tomorrow your day one. Because sometimes reinvention doesn't arrive with a grand announcement. Sometimes it quietly wanders in while you're busy doing something else. That is how I wrote a book. And perhaps more importantly, that is how I discovered I wasn't finished becoming whoever comes next. It is never too late. If not now, when? Sue My Book is Available for Order: I hope you will consider ordering a copy of Your Retirement Reset for yourself, a friend, or someone you love. Published by ECW Press and is available through Indigo or Amazon and McNally Robinson. If you like supporting Canadian booksellers, check with your local independent bookstore too. Most can order it.

Peri-Retirement: The Life Stage Nobody Told Us About featured image

7 min

Peri-Retirement: The Life Stage Nobody Told Us About

It started with the sweating. Not the kind you get after a workout, or the kind that shows up when you realize you're late for a job interview. This was different. Our patient, a perfectly healthy 48-year-old man, would be sitting quietly at his desk when a wave of heat would roll over him out of nowhere. His shirt would stick to his back, his forehead would glisten, and he would find himself wondering if his wife had quietly turned up the thermostat. Then came the mood swings. One minute he was fine. The next, he was irrationally furious because his wife had asked what he wanted for dinner. "I DON'T KNOW!" he shouted. "I'VE BEEN MAKING DECISIONS FOR THIRTY YEARS! CAN SOMEONE ELSE PICK FOR ONCE?" Then came the 3:17 a.m. panic attacks, always at 3:17, as if his subconscious had set an alarm. He would wake with his heart pounding, one thought looping through his mind: what if I don't have enough? Enough what? He couldn't say. Enough money, enough retirement savings, enough time, enough health, enough golf. He wasn't taking any chances. By 4:03, he was calculating the future value of his RRSP. By 4:27, he was checking his house's value. By 4:41, he was browsing real estate listings in Portugal. By 5:15, he had determined he could not, in fact, afford Portugal. By 5:22, he was oddly angry about a country he had never planned to move to. His wife finally insisted he see a doctor. The doctor listened carefully, ran the usual tests, folded his hands, and delivered his verdict. "I know what's wrong with you." The man sat up straighter. "Is it serious?" "I'm afraid you're suffering from Peri-Retirement." "Peri what?" "Peri-Retirement." "Is it contagious?" "No." "Curable?" "Not exactly." "Am I going to die?" The doctor paused for a long moment. "Eventually. We all will." "That isn't particularly reassuring." "Sorry. The good news is that Peri-Retirement is completely normal. You're 48. You've spent 25 years building a career, raising a family, paying down a mortgage, and accumulating money. You've simply reached the point where you're starting to wonder what comes next." Welcome to Peri-Retirement. And yes, unlike Peri-Menopause, this one is refreshingly inclusive. It affects men, women, and everyone in between, because apparently anxiety about money doesn't check your chromosomes before it shows up at 3:17 a.m. Maslow Could Have Used a Sequel In 1943, Abraham Maslow published his famous hierarchy of needs, the pyramid every psychology student eventually draws on a napkin. It charts the climb from food and shelter to belonging and esteem, all the way to self-actualization, the state of finally becoming the person you were capable of being all along. It's a genuinely useful map of human development. I just think Maslow wrapped it up about one life stage too soon. After decades of working, raising kids, building a career, and accumulating enough assets to make an accountant blush, most of us hit another transition Maslow never got around to charting. Retirement stops being a hazy concept involving golf and starts feeling uncomfortably real. I call that first stage Peri-Retirement, and I'd put it roughly between ages 45 and 60, the years when retirement starts creeping into every quiet moment. When can I actually retire? Will I have enough? What will I do with my Tuesdays? Can I afford to travel? What happens if I live to 95? And the question that keeps people up at 3:17 in the morning: who am I if I'm no longer working? After that comes Pre-Retirement, roughly 55 to 70. For many Baby Boomers, working until 70 has quietly become the norm, so the old assumption that everyone retires neatly at 65 is starting to look about as current as a rotary phone. Then comes Retirement itself, which turns out to have three distinct acts. There are the Go-Go years, when health and energy are still on your side and people travel, renovate the kitchen, take up pickleball, or try to figure out why everyone suddenly won't stop talking about it. Then the pace naturally shifts into the Slow-Go years, when spending and activity ease off. Eventually come the No-Go years, when health or mobility start setting the boundaries. Retirement, in other words, can run for three decades, and the financial life of a 65-year-old looks nothing like that of an 85-year-old. Which brings us to a problem the industry has grown remarkably comfortable ignoring. The Gap Between Net Worth and Cash Flow We have all become fluent in net worth. We know what our homes are worth, down to the last renovation; we track our RRSPs and TFSAs like box scores; and we celebrate or panic depending on which way the portfolio moved this week. Net worth and cash flow, though, are two completely different animals. Net worth tells you what you own. Cash flow tells you what you actually have available to pay for your life. You can be asset-rich and cash-flow poor at the same time, sitting in a million-dollar house while stressing over the hydro bill, because the grocery store still hasn't rolled out a "pay with bathroom renovation" option. That gap between paper wealth and usable income is one of the biggest problems facing retirees today, yet it gets a fraction of the attention it deserves. Turns out I'm not the only one losing sleep over this at 3:17 a.m. I co-authored a paper with EY called Canada's Retirement Evolution, and the numbers we pulled together read like a diagnosis. About 30 percent of Canadians are already 55 or older, and that share could climb to between 35 and 40 percent by 2030. Layer on top of that a trillion dollars in wealth moving from Baby Boomers to their Gen X and Millennial kids between 2016 and 2026, with roughly 70 percent of it tied up in real estate, and you get an entire country full of people who are asset-rich, cash-flow-anxious, and one awkward Thanksgiving dinner away from an intergenerational conversation about the house. We Got Very Good at One Half of the Job For decades, the financial services industry trained us beautifully in exactly one skill: accumulating. Save into your RRSP, max out your TFSA, diversify, pay down the mortgage, build the portfolio, grow the assets. Most of us became excellent students. The trouble is that the assignment eventually changes. At some point, accumulation has to hand the baton to decumulation, and we're suddenly expected to figure out how to convert decades of saving into income that can fund the rest of our lives. Ideally without draining the account, spooking ourselves every time the market dips, or spending our seventies squinting at investment statements at 4 a.m. We get thirty or forty years of coaching on how to put money into the machine, and then almost none on how to dispense it safely. That's exactly where Peri-Retirement gets interesting. What If the Income Conversation Started Earlier? The Peri-Retirement crowd is sitting on an asset most retirees have already spent: time. These are people still working, often earning meaningful income, with savings, home equity, and years for that money to compound before they need it. That's a real opportunity for the financial services industry; one it has largely left on the table. What if retirement income wasn't something we only started thinking about the week before the retirement party? What if there were products built specifically for the Peri-Retirement years, ones that let people work toward predictable, guaranteed income for life, starting at an age they choose? The idea deserves serious attention. Waiting until retirement to solve the income question means giving up years of compounding and cramming an enormous decision into a painfully short window. Starting earlier lets people build that income gradually, while a paycheque is still coming in to fund it, and it changes the whole conversation. Instead of only asking "how much money will I have when I retire," we could start asking "how much income will I actually need, and how do I build it before I get there?" That's a fundamentally different way to plan for retirement, and it might be exactly what Peri-Retirement is for. Our 48-year-old patient may have shown up with hot flashes, mood swings, and a standing 3:17 a.m. appointment with his own anxiety, but his body wasn't betraying him. It was trying to get his attention. Peri-Retirement might be the moment we finally understand that retirement was never just about the number in the account. It's about knowing exactly how that number translates into a life you can afford to live, for as long as you're living it. That's the question I wrote Your Retirement Reset to answer, including the one that trips up almost everyone: how do you turn what you've accumulated into sustainable income and cash flow for the years ahead? The book hits stores and libraries on September 29, and you're welcome to grab a copy directly from me. If you have a parent circling retirement, buy two. Retirement has a funny way of becoming a family sport, whether anyone signed up for it or not. As for our patient, the doctor sent him home with a retirement plan, a firm suggestion to stop checking his RRSP before sunrise, and strict orders to close every tab related to Portuguese real estate. His prognosis is excellent. He has Peri-Retirement, and now, at least, he finally knows what to call it. The financial industry, meanwhile, is still mostly asleep at 4:03 a.m., and it's about time someone woke it up! Don’t Retire… ReWire! Sue My Book is Available for Pre-Order: I hope you will consider pre-ordering a copy of Your Retirement Reset for yourself, a friend, or someone you love. It arrives September 29, 2026, published by ECW Press, and is already available through Indigo or Amazon. If you like supporting Canadian booksellers, check with your local independent bookstore too. Most can order it.

View all posts