When Two Retirements Collide

For Better or Worse, Or Until Tuesday

Oct 14, 2026

8 min

Sue Pimento

All this talk lately about Trump and Carney squaring off has made me reflect on matters closer to home. My living room has never quite reached the level of a televised leaders’ debate, but retirement has a way of turning minor domestic disagreements into full parliamentary sessions. And unlike politicians, you can’t call a recess and fly to Florida.


For years, we’ve been sold a lovely picture of retirement. The alarm clock disappears. The kids have finally stopped treating your house like a storage locker. There are leisurely breakfasts, travel, golf, grandchildren, and coffee on the patio on a Tuesday morning simply because you can. And there is your spouse. Every. Single. Day.


For many couples, this is wonderful. Even in the happiest relationships, though, somewhere around the third consecutive Tuesday morning together, a thought may quietly surface: Have you always chewed like that?


We spend years trying to figure out whether we have enough money to retire. We calculate pensions, RRSPs, CPP, home equity, and how long our savings might last. We consult financial planners and make budgets. Some of us even build colour-coded spreadsheets, which I think is taking things a little far (just saying). Far fewer couples spend time figuring out how they will retire together, and that’s a different calculation altogether.


Two Retirement Plans before One


During our working years, most couples have something that retirement quietly removes: separation. You go to work. I go to work. You have your colleagues, routines, frustrations, and responsibilities, and I have mine. We leave each other in the morning, collect a day’s worth of stories, and come home with something to talk about. Retirement can fold two fairly independent lives into the same house and the same calendar, usually by the first Monday.


Research backs this up. A German study of 2,117 couples, drawing on more than 30 years of national survey data, found that on average both partners grew more satisfied with life around retirement. The changes were also highly correlated within couples, so when one partner’s satisfaction slipped, the other’s tended to slip right along with it (Weber et al., 2021). Your retirement becomes my retirement, whether I applied for the position or not.


Then come the expectations. One person has been dreaming of travelling for 20 years. The other would happily never set foot in an airport again. One wants to move, and one wants to stay. One wants to golf four days a week. The other thought retirement meant finally doing things together. One wants to help the kids financially. The other believes the kids are 43 and it may be time they gave adulthood a whirl.


Even the timing can cause friction. One of you retires in June, the other has three years left before the pension kicks in, and suddenly someone is home all day reorganizing the spice drawer. Research on how couples make retirement decisions suggests that the way the call gets made, and whether both people feel they had a say, shapes how satisfied they are with retirement afterward (Szinovacz & Davey, 2005). The relationship you bring into retirement also comes along for the ride. Old patterns of closeness and conflict travel with you like carry-on luggage, and retirement simply changes the scenery around them (Davey & Szinovacz, 2004).


That makes me wonder whether every couple needs two retirement plans before they have one. What does your retirement look like? What does mine look like? Where do they overlap? Those questions may matter more than whether we can afford the Viking cruise.


And Then There’s Money


Of course there is. Money has always had an extraordinary ability to walk into a perfectly pleasant conversation and leave with a baseball bat. In retirement it gets even more emotionally charged, because our financial psychology shifts. During our working years, another paycheque is always coming. In retirement, many of us start drawing down assets we spent decades building, which can feel completely sensible to one spouse and mildly terrifying to the other.


This is where FORO, Fear of Running Out, can pull up a chair at breakfast. One partner sees $800,000 as security. The other sees the same $800,000 as a number that can only get smaller. Suddenly a $12,000 trip to Italy is carrying a lot of luggage: safety, control, mortality, and whether 93-year-old you might someday need that money.


Then health can change the equation again. A spouse gets sick. Mobility changes. One person becomes a caregiver, and independence starts to slip away. Retirement plans that once looked beautifully aligned suddenly don’t, and that is a lot of change for any relationship to absorb.


Apparently, Fighting Isn’t Necessarily Bad


Three very different thinkers have helped me rethink the whole subject: an ancient Chinese general, a modern conflict facilitator, and a psychologist with a lab full of arguing couples.


Sun Tzu’s The Art of War is about military strategy, yet one of its most enduring ideas travels surprisingly well into marriage: understand the situation, understand the other person, and don’t waste resources on battles that don’t need to be fought.


Priya Parker comes at conflict from almost the opposite direction in her new book, The Art of Fighting (2026). Her work explores how conflict can strengthen relationships when people engage with it well. She calls this idea “healthy heat.” Some difficult conversations need enough heat to burn through to what actually matters.


Then there is psychologist John Gottman, who studied couples over time and found something I love: happy couples don’t all fight the same way (Gottman, 1993). His research identified three stable types. Validators calmly talk their disagreements through. Avoiders would much prefer to change the subject. Volatile couples argue loudly and passionately and keep their marriages intact anyway. The couples headed for trouble were the hostile ones, along with the ones who had quietly checked out.


So you and I don’t have to argue like the nice couple down the street. They look exhausted and bored, to be frank. What seems to matter is whether we can disagree and still hold on to respect, affection, and the sense that we are on the same side. That calls for something to sit beside the retirement financial plan.


The Retirement Rules of Engagement


1. Figure out what you’re really fighting about. Before digging in your heels, ask why this matters so much to each of you. The argument about selling the house may really be about losing independence. A fight over spending can be tangled up with FORO. Too much golf might be about purpose for one person and loneliness for the other. And the argument about money may have very little to do with the actual numbers. Once the real issue is on the table, at least you’re having the right argument.


2. Choose your battles. Sun Tzu would make an excellent retirement consultant. Some things matter enormously, and others really don’t. If your spouse has loaded the dishwasher incorrectly for 37 years and everyone is still alive, victory may no longer be strategically important.


3. Keep the heat healthy. Disagreement has a place in a strong relationship. Parker’s idea of healthy heat gives us permission to have uncomfortable conversations without treating the discomfort as proof that the relationship is in trouble. Say the difficult thing. Ask the awkward question. Then stay curious about the answer.


4. Remember who is sitting across from you. This is the person you chose to build a life with. Opposing counsel bills by the hour. Gottman’s research is especially useful here, because hostility and emotional disengagement are the real warning signs. Anger passes. Contempt has a nasty habit of moving into the spare room.


5. Build some mine, yours, and ours. Two people don’t need to become one organism to have a good retirement. Separate interests, friendships, and activities give each partner purpose and independence, plus fresh material for dinner conversation. Then build the shared things on purpose too: travel, grandchildren, exercise, volunteering, cottage time, date nights, or whatever makes retirement feel like ours. A little absence can still make the heart grow fonder.


6. Know when you’re stuck. If you keep having the same argument, if conversations regularly turn hostile or contemptuous, or if one of you has simply stopped engaging, outside help may be worth it. A couples therapist can untangle relationship patterns. A financial planner can put real numbers around money fears. A retirement coach can help when identity and purpose are causing friction. Sometimes the most useful person at the kitchen table is the third one.


What About Grey Divorce?


Grey divorce is worth a few minutes here, because ending a marriage later in life is especially hard to recover from financially, and it ripples through the whole family, right down to the grandchildren who now spend Christmas in two places.


The Canadian story, however, is less dramatic than the headlines suggest, partly because so many of those headlines are American. In the United States, adults 50 and older made up 8% of all divorces in 1990 and nearly 40% in the latest figures, and their divorce rate doubled between 1990 and 2010 before levelling off (Westrick-Payne & Brown, 2024). Canada never had that boom. Statistics Canada reports that the divorce rate among Canadians aged 50 and older rose 26% between 1991 and 2006, from 4.2 to 5.3 divorces per 1,000 married people, and has since remained relatively stable (Statistics Canada, 2022). Grey divorce remains considerably less common here than divorce among younger adults, so if you’ve read that it has doubled, you were reading about Americans.


Still, divorce at 65 is financially different from divorce at 35. There are fewer working years to rebuild. One household becomes two. Housing, retirement income, pensions, estate plans, and family relationships can all take a hit, and women tend to feel it most. A Statistics Canada study that tracked Canadians from their mid-50s into their 70s found that divorced women kept about 70% of their family income, compared with about 87% for women who stayed married (Mehdi, 2023). The study concluded that divorce lowers living standards in retirement more than the death of a spouse does.


Till Death Do Us Part Is Longer Than It Used to Be


A couple retiring in their 60s could easily have another 20 or 30 years together. That’s an extraordinary gift. It’s also a very long time to argue over the thermostat. Our health will change, our finances may shift, and our interests will wander off in directions neither of us saw coming. The people we were when we walked away from our careers won’t necessarily be the people we are at 75, 80, or 90, so our relationships need room to grow with us.


So pick the battles worth fighting, bring a little healthy heat to the ones that matter, and concede the rest, especially the dishwasher. Thirty years of retirement works out to more than 1,500 Tuesdays together. It would be a shame to spend them arguing about the forks.


Don’t retire. ReWire.


Sue


P.S. Retiring solo? Don’t get too comfortable. Many of the same issues show up with adult children, friends, and family, along with everyone’s sudden assumption that you now have all kinds of free time. I’ll tackle that one in two weeks.


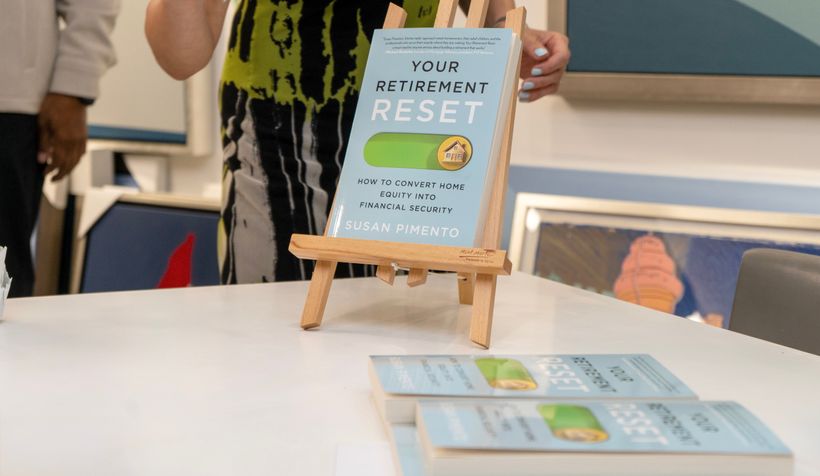
My Book is Available for Order: I hope you will consider ordering a copy of Your Retirement Reset for yourself, a friend, or someone you love. Published by ECW Press and is available through Indigo or Amazon and McNally Robinson. If you like supporting Canadian booksellers, check with your local independent bookstore too. Most can order it.

Connect with:
Sue Pimento

Sue Pimento

Founder | CEO

Writer, author & presenter focused on financial literacy and retirement strategies. I advocate for the health, wealth & purpose for retirees

Public speaking & trainingFitness and WellnessBankingPension ReformInterest Rates
Powered by

You might also like...

Check out some other posts from Retire with Equity

Retiring Solo: Table for One? featured image

10 min

Retiring Solo: Table for One?

In my last article, I wrote about couples retiring together. The dishwasher. The thermostat. The 1,500 Tuesdays. If you are retiring solo, you may have read it with a certain amount of satisfaction, thinking, Thank God I don't have to deal with that. Sorry. This week is about you. There are, admittedly, some advantages to retiring solo. Nobody questions why you bought another pair of golf shoes. The thermostat stays exactly where you left it. If the dishwasher is loaded incorrectly, the list of suspects is short. You can eat dinner at 4:30 or 9:00, watch whatever you want on television, and go to bed with a book without anyone asking when you are going to turn out the light. But retiring solo has its own complications. While you may be living without a partner, you aren't retiring without relationships. In fact, those relationships may matter more than ever. Adult children, siblings, friends and neighbours begin to take on different roles in our lives. Work friendships fade. Social circles shift. Things we once did as two may now have to be done as one. Underneath all of that is a question we don't spend nearly enough time thinking about when we plan for retirement: Who are your people? When Solo Wasn't the Plan There are people who retire solo by choice, people who arrive there after a divorce, and people who would give almost anything not to be there at all. Statistics Canada reported that 4.4 million Canadians lived alone in 2021, representing 15 per cent of adults. Living alone becomes increasingly common as we age (Statistics Canada, 2022). But numbers can only tell us how many people live alone. They can't tell us how they got there, and that matters. For someone who has lost a spouse after decades together, solo life isn't necessarily an exciting new chapter of independence. There is an empty chair at dinner and a quietness in the house that wasn't there before. But I suspect some of the hardest losses are much smaller. There is nobody to ask whether you fed the dog, what time you want to leave, whether you need anything from the grocery store, or what you feel like having for dinner. Nothing profound, just thousands of tiny conversations that made up a life. The older I get, the more I realize how much of life unfolds in those unremarkable moments. We photograph birthdays, weddings, anniversaries and vacations, but sometimes the person drinking coffee across from you on an ordinary Tuesday morning turns out to be the event. For anyone who finds themselves alone because somebody died, I think we need to be careful with our cheerful retirement advice. There is no timetable for rebuilding a life, and grief doesn't respond well to project plans, motivational sayings or well-meaning people telling you it's time to "get out there." Eventually, though, perhaps the question begins to change. "How do I live without this person?" can slowly become "What might my life become now?". That isn't replacing anyone. It's continuing, carrying them with you. Living Alone and Being Lonely Are Not the Same Thing You can live alone and have a wonderfully full life. You can also be married and profoundly lonely. A second toothbrush has never been a reliable measure of human connection. Still, retirement removes something many of us didn't realize work was providing: a surprising number of people. Think about an ordinary working day. Someone says good morning. Someone asks about your weekend. There is coffee, hallway chatter, gossip, meetings, lunch, and the person who drops by your office to tell you something that absolutely could have been an email. None of those interactions seemed particularly important at the time, but together they created the social fabric of the day. Then one Friday you retire, and come Monday morning, most of it is gone. Research supports what many retirees discover instinctively. Social isolation and loneliness are related but not the same. Low social participation among older Canadians has been linked to poorer health and a higher risk of mortality. In other words, those seemingly insignificant interactions may not be so insignificant after all (Gilmour & Ramage-Morin, 2020). I see a version of this in the fitness classes I teach. People don't just arrive, exercise and leave. They come early. They talk. They know who has a bad knee, who just got back from Florida, who has a grandchild who got into university, and who hasn't shown up for a couple of classes. Sometimes I think the ten minutes before class are every bit as important as the class itself. Someone is expecting you, and there is something wonderfully ordinary and incredibly important about that. Who Are Your People? Couples tend to have a built-in default. Something happens, and you tell your spouse. You need a ride home after a medical procedure, and there is an obvious candidate. You have a terrible day, hear a ridiculous story, or get wonderful news, and you know who you're going to call first. When you're solo, that role can gradually shift to a best friend, sibling, neighbour or adult child. Before long, one person has become the emergency contact, travel companion, dinner date, sounding board, tech support and the person expected to answer the phone when something goes bump in the night. That's a fairly demanding job description. Your daughter may adore you, yet not want to be your entire social life. Your best friend may love travelling with you, but occasionally want to travel with someone else. Your sister may happily drive you home from a colonoscopy. Friendship has limits, but apparently that isn't one of them. Maybe the answer isn't to find your person at all. Maybe it's to find your people. Who could you call at 2 a.m.? Who makes you laugh? Who would notice if you hadn't heard from them for a few days? Who knows when you need company and when you need to be left alone? Who can tell you you're being ridiculous and still survive the experience? We have spent decades being told to diversify our investment portfolios. I think our relationship portfolios deserve the same consideration. And there is another side of independence that we don't talk about enough. Independence is wonderful, right up until the day you get tired of it. There is a difference between being perfectly capable of handling something yourself and occasionally wishing you didn't have to. The furnace breaks, the car won't start, or you have an important medical appointment, and, of course, you can deal with it. Sometimes what you miss isn't help. It's backup. Someone who simply says, "I'll come with you," even though you both know you could go alone. Your Children Love You. They Also Have Lives. Retirement can rewrite the relationship with adult children, too. You retire, and they hear: Mom has time. Suddenly there are grandchildren to pick up, dogs to sit, deliveries to receive, and errands that somehow land on the desk of the person who no longer has one. Much of this can be wonderful. Having more time for family is one of retirement's great gifts, and being involved with grandchildren can bring enormous joy and purpose. But helping can quietly become being on call, just as needing companionship can quietly become expecting your children to provide it. Nobody has necessarily done anything wrong. The relationship changed, and nobody held a meeting. So maybe hold one. Your children can be an important part of your retirement without being responsible for creating it, and you can be important in their lives without automatically becoming the unpaid Uber driver, dog walker, daycare provider, or the person who waits between noon and 5:00 for the new dishwasher to arrive. Love each other. Help each other. Just don't confuse retirement with unlimited availability. Learning to Occupy the World as One Then there are all the little firsts. The first restaurant. The first trip. Maybe, eventually, the first date. You walk into a restaurant and say, "Table for one." The host smiles brightly. "Right this way," and off you go, past the tables by the window, past the cozy booth, and around the corner to a tiny table directly outside the noisy kitchen door. Apparently, this is where they keep the single people. "Table for one" can be funny until you remember that, for some people, it used to be a table for two. But I wouldn't give up restaurants because of it. Sit at the bar. Bring a book. Become a regular somewhere. Ask another solo friend to join you sometimes, and other times don't. Take yourself somewhere nice because good food and a decent table aren't benefits reserved for couples. I especially wouldn't overlook the neighbourhood diner or watering hole. These places often become little communities. One of the women in my spinning class is in her 80s and started a euchre club that became so popular that she now has a waiting list. I love that story because she didn't wait for someone to invite her into a social life. She created one and then invited everybody else. Sometimes community isn't something you find. It's something you build. Travel requires a little nerve, too. There is something liberating about choosing where you go, when you get up, and whether visiting six museums in one afternoon sounds fascinating or like a human-rights violation. Then you discover the single supplement, the travel industry's charming way of saying, "Congratulations on your independence." That will be another $1,800. There may also be a moment when you see something beautiful and instinctively turn to share it with someone who isn't there. That's the part the travel brochures don't mention. But there may also come a morning when you realize you've travelled to somewhere you wanted to go, figured it out, and had a wonderful time. Both feelings can be true. And then, perhaps, there is dating. If you're my vintage, you may remember the old Canadian Togethers dating-service commercial: "Adult, alone, unattached? Tired of the bar scene?" I can practically hear it. Back then, joining a dating service seemed positively daring. Today, strangers can reject one another from the comfort of their sofas with a single swipe. Apparently, this is progress. Some people would rather have another colonoscopy. Others discover, happily, that companionship, romance and sex did not get the memo about retiring at 65. Enjoy it. Take your time. Keep your head along with your heart. Being 70 does not make everyone trustworthy. Age brings wisdom, just not universally. Make Yourself Expected Somewhere The more I think about solo retirement, the less I believe the goal is to ensure you're never alone. Solitude can be wonderful. There is pleasure in having your own space, your own routines, and no one asking why you're eating cereal for dinner. What matters is having somewhere you belong. Become a regular at the coffee shop where they know your order. Join the fitness class where someone notices when your bike is empty. Volunteer somewhere that counts on you. Make the lunch date. Know your neighbours. Join the euchre game, or, like my spinning participant, start one. Put things on the calendar, because Tuesday can quickly become Friday when nobody expects you anywhere. And don't just build a life full of people you can call when you need something. Build one where people call you. Be the person who remembers a birthday, walks someone's dog when they're sick, makes the lasagna, gives a ride, listens to the story, or notices when someone else hasn't shown up. There is enormous purpose in being needed. Connection isn't simply having a support system. It's participating in other people's lives and allowing them to participate in yours. The Public Health Agency of Canada identifies retirement, illness and the loss of a spouse as later-life transitions that can strain our sense of independence and connection, and encourages older adults to stay connected with family, friends, health professionals and community organizations (Public Health Agency of Canada, n.d.). That sounds very official. I would translate it more simply: keep showing up. And if your world starts to feel smaller, pay attention. If loneliness becomes persistent, tell someone. Call a friend. Talk to your doctor. Look for a community group. In Canada, 211 is a free and confidential service that connects people with government and community-based, non-clinical health and social services. In most of Canada, you can simply dial 2-1-1 (211 Canada, n.d.). Asking for company isn't imposing. You may find the other person was hoping someone would call, too. We spend a lot of retirement planning asking whether we have enough money. If you're retiring solo, perhaps there are two other questions worth asking just as seriously: Who are my people? And whose person am I? Maybe that's the real difference between retiring solo and retiring alone. One describes who lives in your house. The other describes how you live in the world. So build your community before you desperately need one. Be brave enough to walk into the restaurant, book the trip, take the class, call the friend, and occasionally admit you'd like some company. Create reasons to get dressed in the morning and places where someone notices your arrival. More importantly, create a life in which your absence would leave a small hole in someone else's day. And if the restaurant tries to seat you beside the kitchen, smile and ask for the table by the window. The couples get the dishwasher. Surely we can give the solos the good table. Don’t retire... ReWire! Sue My Book is Available for Order: I hope you will consider ordering a copy of Your Retirement Reset for yourself, a friend, or someone you love. Published by ECW Press and is available through Indigo or Amazon and McNally Robinson. If you like supporting Canadian booksellers, check with your local independent bookstore too. Most can order it.
Why the retirement plan that worked for your parents is failing millions of Canadians featured image

4 min

Why the retirement plan that worked for your parents is failing millions of Canadians

Last month, I found a jar of mustard at the back of my fridge with a best-before date of 2019. It looked and smelled fine. My wife watched me unscrew the lid like I was about to eat gas-station sushi, and I threw the mustard away. I wish Canadians gave their retirement plans the same hard look, because most of the advice we hand people over 55 carries a best-before date of 1990, the year my parents' retirement began. They met at the grocery chain where they both worked, and each left with a defined-benefit pension: a monthly cheque that arrived for the rest of their lives, regardless of what the stock market did. Their employer bore the investment risk. Their job was to show up at the retirement party and eat the cake. That plan stood on three legs: a workplace pension, CPP and Old Age Security, and a paid-off house you would eventually sell to trade down. In 1991, a 65-year-old Canadian man could expect to live about 16 more years and a woman about 20. A plan built for that stretch did its job. Look at those legs today. Only 37.7 per cent of paid workers in Canada belonged to a workplace pension plan of any kind in 2023, according to Statistics Canada, and coverage has been declining for two decades. For most people, the cheque that used to arrive like the newspaper has been replaced by a statement that reads like a horoscope. CPP and OAS were never meant to carry anyone alone. That leaves the house. A 2023 CPP Investments survey found that only 45 per cent of Canadians have a financial plan for retirement, yet about three in four Canadians aged 55 to 74 own their homes. For millions of families, the house was the plan: buy it, pay it off, and burn the mortgage papers in a roasting pan. The old playbook still has one instruction for that asset, unchanged since 1990: sell, move, and hope the condo is cheaper. Most like to stay in their neighbourhood. In Toronto, they usually can't afford to. The calendar changed, too. My parents' plan was built for that 15-to-20-year stretch. Today, Canadian financial planning standards give a 65-year-old couple an even chance of one living to 94, a retirement closer to 30 years. That is about 10 extra years of groceries, property tax and dental work, and nobody gave the plan a raise to cover them. Larry Fink, who runs BlackRock, put his finger on it in his 2024 letter to investors: we have worked hard to help people live longer and much less hard to help them afford those extra years. Those years arrived just as the guaranteed pension cheque was disappearing, a change Fink called "a shift from financial certainty to financial uncertainty." When the man in charge of the world's largest pile of other people's money says so, I'd put down the mustard. Our system does a fine job of helping people pile up money, then goes quiet the moment they need that pile to become a paycheque. We hand people a savings target, a risk questionnaire and an RRSP deadline. On their last day of work, we hand them a bouquet. How much do you withdraw? Which account first? What happens to your OAS when your RRIF minimum pushes you past the clawback threshold? Where does the house fit? The old plan shrugs. The strain shows. Statistics Canada reports that among Canadians aged 65 to 74 who worked in 2022, almost half did so out of necessity. After a late-life divorce, my mother returned to part-time work at a grocery store. She had done everything the old plan asked of her. The usual reply is that people just need to save more. Telling a 72-year-old to save more is like telling a marathoner at kilometre 40 to train harder. An up-to-date plan opens with the question that matters at 65: how will this money cover the bills for 30 years? Home equity goes on the balance sheet at the first meeting, pulled from the drawer marked "emergencies and inheritance." Ninety-one per cent of Canadians say they want to live independently in their own homes for as long as possible, so a good plan offers ways to do that beyond a For Sale sign. And the industry that spent 40 years teaching people to save owes them the same energy in how to spend it. I have a modest proposal for the banks. Every February, you run RRSP season, complete with sailboat commercials. Give us an RRIF season to match, with the same budget, and put a drawdown plan in front of every client who turns 65. And while you are at it, switch the word "savings" to "spending" or "paycheque" on our bank account. Take your retirement plan out of the back of the fridge and check the date on the lid. If it says 1990, you know where it goes. My wife will be happy to show you the garbage. This Opinion Article was published in the Business Section of the Saturday Star and online Toronto Star on October 17, 2026, 

MEDIA ADVISORY: “Your Retirement Reset” by Canadian Retirement Expert Susan Pimento Arrives in Bookstores Across Canada featured image

3 min

MEDIA ADVISORY: “Your Retirement Reset” by Canadian Retirement Expert Susan Pimento Arrives in Bookstores Across Canada

Practical guide to turning home equity into lasting retirement income is now available at Indigo, independent bookstores, Amazon.ca and McNally Robinson, and through Simon & Schuster in the U.S., in paperback, ebook and audiobook. Pimento is on a national media tour. TORONTO, ONTARIO, CANADA, September 29, 2026 -- Many Canadians share the same quiet worry: running out of money before they run out of life. Retirement expert Susan Pimento has a name for it: FORO, the Fear Of Running Out. As of today, her answer to it is in bookstores across the country. Your Retirement Reset: How to Convert Home Equity into Financial Security, published by ECW Press, is now in stores nationwide, including Indigo and Chapters locations and independent booksellers. It is also available on Amazon.ca and from Canadian independent bookseller McNally Robinson, in trade paperback, ebook and audiobook. In the United States, readers can order the book through Simon & Schuster. The book is written for Canadians in or near retirement and for the adult children who help them plan. It addresses a gap in how Canadians talk about retirement. Most advice is about saving. Very little explains how to turn what people have built into steady income that lasts. For many retirees, the family home is their largest asset. Your Retirement Reset explains, in plain language, the tools Canadians can use to unlock home equity. It shows how those tools fit alongside government benefits and registered savings, and how to weigh the trade-offs with family before making a decision. “Canadians have been told to save, save, save. Nobody tells them how to spend it,” said Pimento. “Meanwhile, the biggest asset most retirees own is right under their feet, and they’ve been taught to treat it like it’s off limits. A lot of people are house-rich and cheque-poor. This book is for anyone lying awake at 3 a.m. doing retirement math. You’ve done the hard part. Now let’s make it work for you.” “The book is about something that affects every one of us. How we're going to live and live well in the second half of our lives. Sue challenges us to think differently about retirement, especially the difference between having assets and having the income we need to enjoy life. She also challenges the traditional idea that the equity in our homes should simply sit there untouched until we die. Used thoughtfully and conservatively, she believes home equity can be a part of the retirement income conversation,” said Jennifer Smith, Publisher at ECW Press, at the book launch. National Media Tour Underway Susan Pimento is on a national media tour, and ECW Press is booking interviews with broadcast, print, podcast and online outlets. She can speak to: FORO (the Fear Of Running Out) and why it is keeping retirees up at night How Canadians can use home equity safely as a source of retirement income Common myths about reverse mortgages and downsizing What the shift from defined benefit to defined contribution pensions means for today’s retirees How adult children can start the money conversation with their parents To request an interview, contact Cassie Smyth, Publicist, at ECW Press (details below). Readers can find free resources and learn more about Pimento’s work at retirewithequity.ca. Book Details Title: Your Retirement Reset: How to Convert Home Equity into Financial Security Author: Susan Pimento Publisher: ECW Press In stores: September 29, 2026 Formats: Trade paperback, ebook, audiobook Price: $28.95 (Canada); US$28.95 (United States) ISBN (paperback): 978-1-77041-897-4 Pages: 280 US distribution: Simon & Schuster About Susan Pimento and Retire with Equity Susan Pimento is a Canadian retirement expert, author and founder of Retire with Equity, an education and advocacy platform on retirement financing. She spent more than 30 years in banking and mortgage lending, including as a Vice President at a Schedule I bank. She advises financial institutions and policymakers on modernizing retirement solutions for Canadians 55+, and co-authored EY Canada’s report The Canadian Retirement Evolution. Her motto: “Don’t Retire…ReWire!” Learn more at retirewithequity.ca Media Contact Cassie Smyth, Publicist ECW Press cassie@ecwpress.com | 416-694-3348 | info@ecwpress.com

View all posts