website Experts
Connect for media, speaking, professional opportunities & more.

Having property insurance is one thing. Understanding what it covers is another. CAA Insurance Company has released a new Property Insurance Guidebook to help Ontario homeowners, condo owners and renters better understand property insurance, including what different types of coverage mean, questions to ask about their policy and what to consider before making a claim. “Insurance is there to help protect the places and belongings that matter to us, but understanding a policy can sometimes feel overwhelming,” says Elliott Silverstein, Director of Government Relations, CAA Insurance Company. “This guidebook gives Ontarians a practical starting point so they can ask informed questions and have more confident conversations with their insurance agent or broker.” What does property insurance cover? Coverage varies by policy, but common property insurance concepts include dwelling coverage, detached structures, personal belongings or contents, and additional living expenses. The CAA Insurance Property Insurance Guidebook explains these and other common insurance terms in clear, everyday language. What Ontario consumers can learn from the Property Insurance Guidebook The guide provides plain-language information to help consumers understand: Common property insurance terminology Coverage considerations for homeowners, condo owners and renters How replacement value differs from market value How renovations may affect insurance coverage What to consider before a property insurance claim Questions to ask an insurance agent or broker Understanding your property insurance before making a claim Consumers should not wait until they need to make a property insurance claim to learn what their policy covers. Understanding the basics of a policy ahead of time can help consumers identify questions about their coverage and reduce the chance of unexpected surprises. Updated guide helps Ontario drivers navigate auto insurance CAA Insurance has also updated its Auto Insurance Guidebook with information about changes to auto insurance in Ontario. Originally introduced in 2022, the guidebook takes a back-to-basics approach to common auto insurance terms and helps Ontario drivers have more informed conversations about their policies and coverage needs. “Whether someone is protecting their home, condo, apartment or vehicle, they should feel comfortable asking questions about their coverage,” adds Silverstein. “These guides are designed to make insurance information more approachable, so consumers can make informed decisions based on their individual needs.” The guidebooks are educational resources and are not intended to replace the expertise of a licensed insurance agent or broker or provide advice about an individual policy. Consumers with questions about their coverage should speak directly with their insurance representative. Both the Property Insurance Guidebook and Auto Insurance Guidebook are available for download through the CAA Insurance website.

Vanderbilt Index Finds Sustainability Remains a Mainstream Consumer Priority
As companies reconsider environmental commitments and sustainability receives less attention in corporate America, American consumers appear to be holding their ground. The inaugural Vanderbilt Consumer Sustainability Index (VCSI), released today by Vanderbilt University and consumer research company Switch 5, finds broad and consistent commitment to sustainability across the country. The national survey of 2,528 American adults found that 83% score above the midpoint on the new index, with surprisingly small differences across regions, gender and urban and rural communities. The findings establish the first baseline for the VCSI, a new quarterly measure designed to track how Americans’ attitudes toward sustainability change over time. Unlike existing measures focused primarily on climate policy or political attitudes, the VCSI looks at Americans as consumers — what they believe, what they expect from businesses and other institutions, and what they say they are willing to do themselves. The inaugural July 2026 reading places the VCSI at 69.2 out of 100, indicating a moderate-to-strong sustainability orientation among American consumers. The VCSI builds on more than two years of consumer research by Switch 5, which studies the attitudes and behaviors shaping consumer adoption of clean energy and sustainable products. That research has included more than 16 national surveys involving more than 50,000 Americans. The partnership with Vanderbilt brings that work into a recurring academic index designed to provide researchers, journalists, and businesses with a consistent measure of how consumer sustainability sentiment is changing over time. “Sustainability is often discussed through the lens of politics or corporate commitments, but consumer preferences are a critical part of the picture,” said Eric VanEpps, Associate Professor of Marketing at Vanderbilt Owen Graduate School of Management and coauthor of the study. “We created the VCSI to establish a consistent measure of what Americans believe and expect when it comes to sustainability, and to track how those attitudes change over time.” Key Findings from the Inaugural Wave 1. Consumer sustainability orientation is stronger than commonly recognized. 83% of Americans score above the midpoint of 50 on the index, suggesting broad popularity of sustainability. “People might read media coverage about how both public and private investments in sustainability initiatives have been reduced, and how large corporations have pulled back from the climate goals they set a few years ago. But the American public still cares about the environment, and these initial results create a baseline from which we can now measure trends in general sentiment,” said VanEpps. 2. Americans want businesses to lead on sustainability. Nearly nine in ten Americans (87%) want companies to help them be more environmentally friendly, and 85% say corporations bear responsibility for addressing climate change. Support for federal government action to address climate change is similarly high, at 84%, indicating broad public expectation that institutions — both public and private — should be part of the solution. “One thing to note is that most Americans work for either large corporations or the government. So when survey respondents say they want these organizations to address climate change, that is also a likely signal of how they want their employers to act,” said Vanderbilt Law School professor and study coauthor Michael Vandenbergh. 3. Concerns about future generations are widespread. More than four in five Americans (81%) believe climate change will harm future generations, including nearly half (47%) who say it will do a great deal of harm. Parents score meaningfully higher on the overall index than non-parents (72.9 vs. 67.3), suggesting the intergenerational frame is a significant motivator of sustainability commitment. 4. Americans say they are willing to act — including at some personal cost. Nearly three-quarters (74%) of Americans say they are willing to pay a little more for products that are better for the environment, and 72% say they are willing to sacrifice convenience to make environmentally friendly choices. These findings suggest meaningful room for consumer-facing sustainability initiatives that go beyond attitude measurement into behavioral change. 5. Sustainability commitment cuts across demographic lines. Perhaps the most noteworthy finding of the inaugural wave is how narrow the differences are across groups typically assumed to hold divergent views on the environment. Regional differences are minimal, with less than 2 points separating the highest and lowest of the four census regions. The gender gap is 1.5 points, and the urban-rural gap is 3 points. 6. Younger Americans lead, but sustainability commitment is broad across generations. Americans aged 18-34 score 72.2 on the index, compared to 65.1 among those 65 and older — a 7-point generational gap that reflects growing sustainability orientation among younger cohorts. Even the oldest segment sits well above the midpoint of the scale, however, indicating sustainability commitment has broad support across generations. Methodology The inaugural wave of the VCSI was fielded to a nationally representative sample of 2,528 American adults in July 2026, with data collection and analysis conducted by Switch 5 using PureSpectrum and Beacon Research. The 10-item composite index demonstrates strong internal reliability (Cronbach’s α = 0.87). Two sub-indices — Consumer Commitment (5 items) and Climate Concern & Responsibility (5 items) — correlate at r = 0.52, indicating that the two dimensions are meaningfully related but distinct. Full methodology and item-level results are available upon request, with a website currently in development. The next wave of the VCSI is expected to be fielded in October 2026 and released in late fall. Subsequent waves will report the current index level along with wave-over-wave and year-over-year changes.

Family Reunion Month: Seven Simple Tips to Begin Recording Your Family’s Oral History
When families gather together for vacations and reunions, they are often regaled with tales about an older relative’s fascinating life story or firsthand experience as an eyewitness to history. So how do you capture and preserve those precious memories? Historians with Baylor University’s renowned Institute for Oral History, home of the national Oral History Association as well as its regional affiliate Texas Oral History Association, have recorded and preserved oral history memoirs of individuals since 1970. Stephen Sloan and Adrienne Cain Darough Stephen Sloan, Ph.D., IOH director, professor of history and executive director of the national OHA, and Adrienne Cain Darough, M.L.S., assistant director and clinical associate professor, share seven simple best practices to help family members begin oral history conversations that enrich recollections of the past. Seven best practices for family oral history conversations 1. Make sure your family member wants their story to be documented or recorded. That's a very important question to ask ahead of time, Cain said. “Many oral historians have run into the spot where, ‘Oh, my grandpa would be great,’ and you get there and it's like, ‘Grandpa does not want to talk to you.’ So first making sure that they want their story recorded.” 2. Determine the type of recording equipment you want to use. Decide if you want to record your interview with an audio recorder or using a video recording device. The Institute for Oral History offers a helpful resource on choosing the right digital recorder for your needs and comfort level. 3. Do some advance research about your family member’s life and their timeline to help you formulate your questions. You can't just put down a recorder in front of someone and say, "Talk." Are there specific things that you want to know? For example, would your family member recall a specific time in their life or a moment in history that affected them? What were they like in high school and what were things they enjoyed doing? Did they serve in the military? “Doing your research to try to form those questions will help you get around what I will say is the reluctance to talk sometimes,” Cain said. “The favorite thing that I love to hear is, ‘Oh, I don't have much to say,’ or ‘I'm not that important.’ And then you sit down with them, and you listen to their stories, and your mind is just blown by the things that they've seen and experienced.” 4. Ask open-ended questions without making any assumptions. With oral history, Sloan said it’s important not to go into the interview with a specific agenda and try to lead anyone to a certain conclusion. “We can do this very subtly by assuming information, but I can't assume that their experience with that topic is X. That could have been very far from how they encountered whatever event that may have been,” Sloan said. “I've got to allow them to relate to me the ways in which they lived these experiences.” 5. Start with the basics, such as “Where are you from?” When Sloan, Cain and their oral history colleagues conduct an interview on any given topic, they generally begin with some life history of the subject, providing important context for historians. “Ask questions early on that are easy for them to answer: a little bit of the backstory, a little bit of where they're from, where they grew up,” Sloan said. “I want to understand the lens through which they experienced events, and the only way I can do that is, who was this? What was formative in their life growing up? Who spoke into who they were? What did they learn? Where did they go? What did they do? Those are the sorts of things that I would be exploring early in the interview.” One of the questions Cain enjoys asking is, “What did you want to be when you grew up?” There is the standard answer, but she notes that there’s often something that happened that may have changed that trajectory. “You want to give them something that's very easy and comfortable to talk about,” Cain said. “What was your favorite subject, just to see if that was something that continued on in their life. If there's a certain hobby or something that you know they're affiliated with, when did you learn about that? Tell me more. What's your interest in this? And then they'll get to talking.” 6. Make sure you are listening, an important facet of gathering oral history. When conducting an oral history interview, you are not only listening for what they're saying, you're also listening for what they're not saying, Cain said. “Are there things that are being skipped around?” Cain said. “For example, sometimes when you're talking to veterans about their combat experience, they need time. There may be some things they have seen and that may be the first time they're reliving or retelling these stories. And you just have to be prepared for that.” 7. Be patient. It might take your subject some time to warm up to the conversation. Patience is a virtue in oral history interviewing. “If you're talking to someone who is 80, 90 or even 100, that's a lot of memories that they have to go through, so patience is important,” Cain said. Oral History Resources LISTEN: Dr. Stephen Sloan and Adrienne Cain Darough join the Baylor Connections Podcast to share more about preserving oral histories while offering tips for individuals seeking to preserve the stories of family or friends. FREE RESOURCES: Baylor’s Institute for Oral History provides free oral history resources on the IOH website. Get best practices on oral history interviewing, project planning and organization, transcribing interviews, protecting and preserving recordings and conducting phone or Zoom oral history interviews. Looking to know more or arrange an interview with the experts? Simply contact: Shelby Cefaratti-Bertin at Shelby_Cefaratti@baylor.edu today.


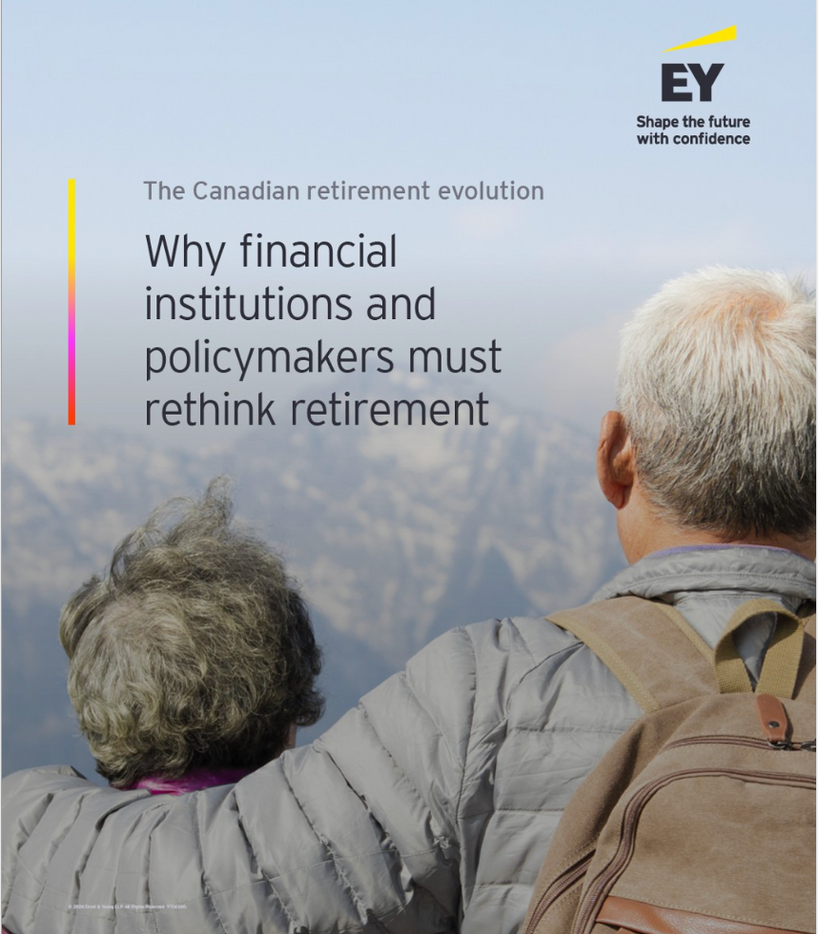
Former bank executive and Retire with Equity founder says "fear of running out" reflects a structural gap in retirement system design — not a failure of individual planning TORONTO, ON — July 23, 2026 — Susan Pimento, founder of Retire with Equity, is a co-author to The Canadian retirement evolution: Why financial institutions and policymakers must rethink retirement, a new report published today by EY examining how Canada's retirement landscape is changing — and why the systems built to support retirees are struggling to keep pace. The report arrives amid a structural shift in how Canadians fund retirement: in 1990, over 70 percent of Canadian workplace pension plans were defined-benefit schemes providing predictable lifelong income; by 2022, that figure had fallen to 37 percent — shifting investment risk, and the fear of running out onto individuals. Drawing on more than 30 years of senior leadership in Canadian banking and frontline lending, including serving as Vice President at a Schedule I bank, Pimento contributed a framework that groups Canadian retirees into three primary categories, each with distinct financial circumstances and priorities — a lens designed to help financial institutions and policymakers move beyond one-size-fits-all retirement planning. Sue Pimento is also the author of the forthcoming Your Retirement Reset: How to Convert Home Equity into Financial Security (ECW Press, to be released September 2026), "Fear of running out — FORO — reflects a structural gap in retirement system design, not a failure of individual planning," said Pimento. "Most retirement frameworks were built for accumulation rather than sustainable income in later life. Canadians aren't failing their retirement plans. In many cases, the plans were never designed for the retirement they're actually living." Pimento's contribution reflects the research focus of Retire with Equity, which provides retirement intelligence to Canada's financial sector on its fastest-growing and wealthiest demographic: adults 55 and over. Her forthcoming book examines how home equity — the largest asset most Canadian households hold — can be strategically converted into retirement income, and argues it belongs in every retirement conversation and product roadmap. "The industry has spent decades perfecting how Canadians save," Pimento added. "The next decade will be judged on how well we help them spend — sustainably, confidently, and without fear." The EY Report: "Canadian Retirement Evolution" is publicly available at: https://www.ey.com/en_ca/insights/financial-services/canadas-retirement-evolution Media availability: Susan Pimento is available for interviews and commentary on: retirement income design the three categories of Canadian retirees financial strategies for aging in place Intergenerational financial conversations about money (between seniors and their adult children) home equity strategies new ways for government and banks to serve the 55+ demographic About Susan Pimento Susan Pimento brings deep experience to the conversation on modern retirement strategies in Canada. With over 30 years of senior leadership in banking and frontline lending — including serving as Vice President at a Schedule I bank — she now advises financial institutions and policymakers on how to modernize retirement solutions and engage Canada's fastest-growing, wealthiest demographic: adults 55+. She is the founder of Retire with Equity and author of Your Retirement Reset: How to Convert Home Equity into Financial Security (ECW Press, September 2026). . Media Contact: Susan Pimento Website: www.retirewithequity.ca Email: sue@retirewithequity.ca

New Gallup–Lumina Study Data Suggests Parents Can't See What a University Degree Is Really Worth
Sixty-three percent of Americans say four-year colleges are doing a poor job of making education affordable. Twelve percent say they're doing well. That figure is getting a lot of attention along with other results in the latest Gallup and Lumina Foundation survey of 2,043 adults. Ironically, this data will surprise very few people working in the sector who are paying attention. When you look at the data, one number stands out and provides hope for institutions. Among parents who hold a college degree, 48 percent want a four-year university for their child. And among parents with some college or a high school diploma, fewer than 20 percent do. Both groups want education after high school. What separates them is whether the parent has personally experienced what a degree does to employment, earnings and job satisfaction. So the case for the four-year degree is currently being carried by "lived experience", which, by definition, does not reach families who haven't had it. These are the families four-year institutions most need to reach. Community colleges, by contrast, show what the alternative looks like when it's explained well. They're rated good or excellent by 68 percent on access, 61 percent on quality, 54 percent on affordability and 52 percent on workforce preparation. Four-year institutions lead in one category: advancing knowledge and new discoveries, 53 percent to 46. Price is where institutions have hurt themselves most directly. Net prices have fallen across income brackets and institution types over six years, yet colleges continue publishing sticker figures that most enrolled students never pay. Courtney Brown calls transparency “the missing link in rebuilding trust.” A family that can't determine the price before applying will assume the advertised number is the price. The 3 Themes Run Through this Data Evidence has to Connect with Audiences Who Have No Reference Point: Institutions often position for families who already understand how higher education works. And the survey suggests the persuadable audience is the one that doesn't. Unexplained Value Doesn't Count: A college credential that costs less, takes two years, and ends in a job explains itself. A benefit that compounds over thirty years does not, and most institutions have responded by falling back on median starting salary. Universities need to show other evidence of value. Scattered Evidence Isn't Discoverable: Aid data, outcomes, faculty expertise, and research impact each live in a different department, in different faculties, and in different systems. It’s challenging for CMO’s to unify all this information. But the market isn’t waiting for that to happen. Students and families now hand that assembly job to an AI search tool, and whatever it retrieves and attributes is functionally what the institution has said. None of this starts with a campaign. Write down the ten questions families ask most often, then check what your website, your faculty pages and an AI assistant currently return for each one. Most institutions find the evidence exists and nobody can locate it. At ExpertFile we understand we can’t fix all of these problems. Nonetheless, we’re working hard to make faculty expertise and research more findable and relatable to a variety of audiences - this includes the students and families that have important questions about the value of university. Americans have not given up on higher education. They just want clearer evidence of what it costs and what it returns, and they want it from credible voices willing to put their names to it.
MEDIA ADVISORY: Your Retirement Reset Book
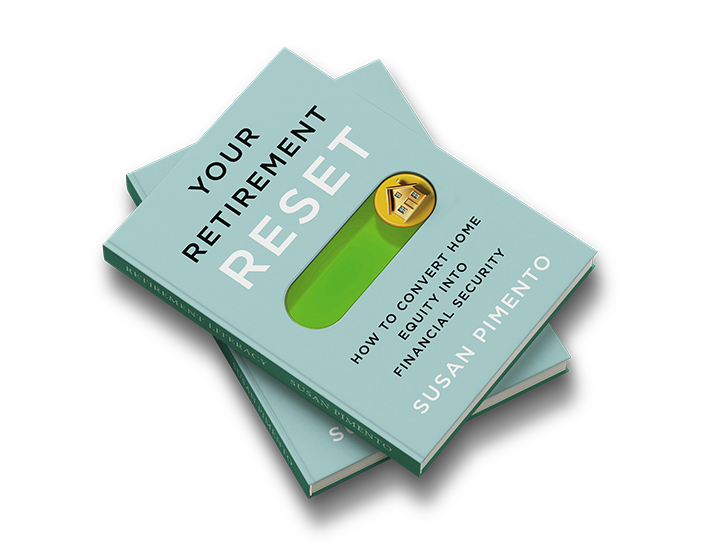
Cover art has been finalized and Your Retirement Reset (ECW Press) is now heading to print ahead of its September 8, 2026 release date. Pre-orders are now available on the ECW Press website. Written for Canadians navigating the realities of modern retirement — and the adult children supporting them — Your Retirement Reset delivers a clear, practical roadmap for converting home equity and other assets into lasting financial security. It tackles the defining challenges of today's retirement landscape: longer lifespans, eroding purchasing power, vanishing pensions, and the near-universal desire to age in place. Susan Pimento brings decades of experience in the financial industry to a conversation that's long overdue — one that goes beyond saving to address how Canadians can strategically and safely spend what they've built. Susan Pimento is available for media interviews and speaking engagements. To arrange, contact: Jennifer Smith ECW Press jsmith@ecwpress.com
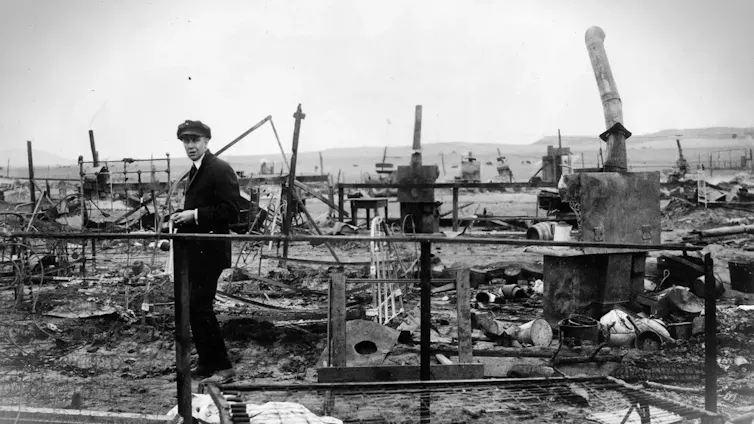
Remembering the Ludlow Massacre of 1914
Mary Anne Trasciatti, Hofstra University’s director of the Labor Studies Program and professor of rhetoric, is referenced in an article on the website Counter Punch about how a dispute for fair wages and safer working conditions led to the 1914 massacre of 25 miners and family members in Ludlow, Colorado. The author, Robert Forrant, notes that he and Dr. Trasciatti co-edited “Where Are the Workers,” a collection of essays written by labor historians and archivists that explore nationwide efforts to bring the history of labor and working people into mainstream narratives of U.S. history. The Ludlow Massacre, he says, is one of the most dramatic and deadly of those stories.


April 1st is the one day we all expect to be fooled. Scammers are counting on the other 364
Breaking News: Free Cruise for All Retirees! Congratulations!!! If you are reading this, you have just been chosen for a luxury Caribbean cruise, a $5,000 shopping spree, and a lifetime supply of… well, something vaguely exciting. All you need to do is: Click this link, enter your banking info, confirm your SIN, and maybe your childhood pet's name for good measure. Still reading? Good. Because if that opening gave you even the tiniest thrill, the little flutter of wait, really? You've just experienced exactly what scammers are counting on. APRIL FOOL'S!!! And also: welcome to the world of phishing. Population: way too many of us. Phishing vs. Fishing: A Retirement Skill You Didn't Know You Needed There are two kinds of fishing in retirement. One involves a dock, a thermos of good coffee, and no deadlines at all. The fish might or might not cooperate. That's fine. That's the whole point. The other scenario involves someone trying to steal your identity by congratulating you on a cruise you never booked, a prize you never won, and a windfall that demands your banking details, your SIN, and, just for fun, the name of your first pet. (Buttons. It's always Buttons.) Let's make sure you're fluent in the first kind and bulletproof against the second. Fraud Doesn't Just Happen to Fools Here's something important to say aloud before we proceed. Fraud isn't caused by people being careless, gullible, or old. It is orchestrated by professionals whose full-time job is to manipulate human behaviour under pressure. There is a clear difference between these two, and how we discuss fraud influences whether victims come forward or stay silent out of shame. This issue is more significant than most realize. Canadians lost over $638 million to fraud in 2024, an increase from $578 million the previous year, according to the Canadian Anti-Fraud Centre. However, that figure only tells part of the story. The CAFC estimates that just 5 to 10 percent of total fraud losses are ever reported. Think about that for a moment. The number we see is already staggering, and the real total is almost certainly ten times higher. Seniors make up a disproportionate share of those losses, especially in investment fraud, romance scams, and the grandparent scam. But here's the part the statistics don't show: fraud is improving at its craft. These aren't the poorly written emails of 2005. Today's scams are refined, patient, and psychologically targeted. They're designed to create urgency, confusion, and fear — aiming to override careful thinking precisely when it's needed most. So let's talk about what that actually looks like. A Very Personal Fraud Story That Will Stay With You A family reached out to me recently, after reading one of my earlier posts on fraud and seniors. Their father had been the victim of a prolonged scam, one that unfolded over months and caused significant financial damage. They only found out after he passed away. Three things about this story stopped me cold. First, their father kept meticulous records. He journaled every interaction, every step, every decision. There was essentially a play-by-play account of how he became entangled and how difficult it became to find a way out. Second, he was an intensely private person. Not a single family member knew any of it was happening while it was happening. Third, he was a chartered professional accountant. Decades of financial training, discipline, and experience. Someone who understood numbers, risk, and how money moves better than most people ever will. And still. Under the right conditions, with the right psychological pressure applied at the right moments, he was drawn in. That is not a story about a foolish man. That is a story about how sophisticated fraud has become. And it is a story that is playing out in living rooms and email inboxes across this country every single day. Why Seniors Are Targeted (And It's Not What You Think) Scammers don't just go after older adults because they think we're naive. They go after us because we have assets. Savings. Home equity. Good credit. Pension income that actually shows up every month. We're not easy targets; we're valuable ones. They also go after us because retirement can come with conditions that fraud is specifically designed to exploit: financial anxiety about making savings last, changes in how we process decisions under pressure, and, for many, reduced opportunities to run something by a trusted person before acting. Social isolation is not a character flaw. It is a vulnerability, and the people running these operations know exactly how to use it. The Scams You Actually Need to Know About The Grandparent Scam. You get a call. It's your grandchild. They're in trouble, arrested, in an accident, stranded, and they need money right now. Please don't tell Mom and Dad. The caller may not even sound exactly right, but panic has a way of filling in the gaps. Sometimes a fake lawyer or police officer jumps on the line to add credibility. The script is designed to bypass your rational brain and go straight for your heart. If this ever happens: hang up. Call your grandchild directly on a number you already have. Every time. The CRA Impersonation Call. This one is especially popular at tax time. An official-sounding voice informs you that you owe back taxes and if you don't pay immediately via e-transfer or gift cards, a warrant will be issued for your arrest. The Canada Revenue Agency does not call you out of the blue demanding gift cards. Full stop. If you're ever unsure, hang up and call the CRA directly as 1-800-959-8281. The Romance Scam. Someone finds you online, charming, attentive, almost too good to be true. Weeks or months in, a crisis emerges. Could you help, just this once? These scams are emotionally brutal and financially devastating. If an online relationship moves unusually fast and a financial request follows, that's not love. That's a script. The Investment Opportunity. Guaranteed returns. Exclusive access. Limited time. These words belong together the way "healthy" and "deep-fried" don't. Legitimate investments don't come with countdown clocks. Phishing Emails and Texts. These mimic your bank, Canada Post, Service Canada, Amazon, and anything you'd recognize. They look almost right. The email address is a little off. The link goes somewhere slightly wrong. They want you to click, to enter information, to act now before something bad happens. The urgency is the tell. No Shame. Seriously. None. If this has happened to you, or someone you love, please hear this: falling for a scam does not mean you are getting old, losing it, or slipping cognitively. It means you are human and were placed under carefully engineered psychological pressure by someone who practices this for a living. That is it. The end. And if you need a reminder that this crosses every age and profession, consider the case of a retired district court judge who lost the equivalent of over $100,000 to a digital arrest scam. Fraudsters called claiming his phone number was linked to a trafficking investigation. Despite decades on the bench watching deception unfold in real time, fear and intimidation did what all that professional knowledge could not protect against. A judge. Still got hooked. That is what these scams do when they are built well. (Source: Devdiscourse) RCMP Sergeant Guy Paul Larocque of the Canadian Anti-Fraud Centre puts it plainly: "Fraudsters are professional salespeople who work a target until they close the deal and get their money." That framing matters. You would not blame yourself for being sold something by a skilled salesperson operating under false pretenses. This is no different. The embarrassment is real and completely understandable. However, it does not fairly reflect what occurred. The CAFC has pointed out that many individuals feel ashamed of being victims of fraud and hesitate to report it, but every report helps break up fraud schemes and protect others. Reporting to the Royal Canadian Mounted Police is not a sign of failure; it is a vital way to safeguard the next person. A Word to Family Members re: Fraud: Drop It Like It's Hot If someone you care about has been scammed, put down whatever you are holding, take a breath, and read this carefully. Do not scold them. Do not lecture them. Do not "grandsplain" them into the ground. Grandsplaining, for the uninitiated, is mansplaining for the aged, and it is just as unwelcome. Nobody needs a slow, patient, thoroughly detailed breakdown of everything they should have done differently while they sit there wishing the floor would open up and swallow them whole. They already know. They feel terrible. They have probably been replaying every moment of it since it happened, asking themselves how they missed it, why they trusted it, and what they were thinking. What they do not need is you asking those same questions out loud. Your role at this moment isn't to be the smartest person in the room. It's not to claim you would never have fallen for something like this. And it's certainly not to start a sentence with "well, I always said you should..." because if you finish that sentence, you're on your own. Your job is to be kind. Full stop. Help them contact the bank. Sit with them while they file the report. Make the tea. Handle the phone call they are too rattled to make. Be the calm in the room. That is what love looks like in a crisis, and this is a crisis. Now here is the part where the tables turn, so pay attention. Scammers are not ageist. They are not sitting in a room somewhere saying, "Let's only go after the over-65s today." They go after anyone with money, a phone, and a moment of distraction. Which means they go after everyone. Your inbox is not immune. Your judgment under pressure is not immune. Your "I would never fall for that" confidence is, frankly, exactly the kind of thing scammers count on. Fraud can happen to anyone, and sharing your experience with others, whether or not money was lost, can help prevent them from being victimized by the same or a similar fraud. Nobody is too sharp, too young, or too digitally savvy to be targeted. The call is coming for all of us eventually. So when it comes for you, and you call your mother in a panic, wouldn't you rather she answer with warmth instead of a very long "I told you so"? Be nice to her now. Consider it an investment. One day, she might be the one sitting you down for "the talk." And at that point, the only appropriate response is to make the tea and keep your opinions to yourself. What the Experts Say: Practical Tips to Stop Fraud In my book "Your Retirement Reset" (ECW Press: Now available for Pre-Order here), I cover the topic of fraud and scams." I wanted to address this issue in depth because fraud prevention is not a footnote in retirement planning. It belongs front and center. Here is an excerpt of Chapter 9 of the book: "Remember the old saying, 'Nothing ever comes free'? While it is hard for many seasoned Canadians not to trust a caller, unfortunately, that's the way of the world today. Here are some tips for protecting yourself. Be skeptical. Be wary of unsolicited phone calls, emails, or messages, especially those asking for personal information or money. Don't take their word for it. Ask the person for their details. If they say they are calling from your bank, get their name and branch number and call your bank for verification. If the message is in an email, contact the institution identified in the email. Do not respond right away, ever. Don't share personal information. Never share personal, financial, or health information with unknown individuals or organizations. Consult trusted individuals. Discuss suspicious offers or communications with family members, friends, or trusted advisors. This is especially important if you are asked to donate to a charity or make any kind of financial investment. Use technology wisely. Install antivirus software, create strong passwords, and stay alert to phishing tactics such as harmful links in texts or emails. Use the block feature on your phone to cut off repeat callers you suspect are fraud artists. Work closely with your financial institution. Ask your bank to send alerts for any unusual activity on your account. Review your statements every month and report unauthorized transactions immediately. Report suspicious activity. If you suspect a scam has targeted you, contact the police. Stay informed. Keep up to date on prevalent scams aimed at older adults. A quick Google search on any unsolicited information request can often tell you whether it has already been flagged. These scams are frequently reported to authorities and featured in the media and on consumer advocacy websites." How to Stay Off the Hook When It Comes to Fraud A little friction can be helpful. Scammers depend on speed, on you reacting before you think. The best thing you can do is slow down. Avoid clicking links in unexpected messages; instead, go directly to the company's website by typing it yourself. Call back on a number you find independently, not one provided in the suspicious message. Check email addresses carefully, as a transposed letter can sometimes be all it takes. Keep your devices updated, since those updates fix real vulnerabilities. Discuss these topics openly. With your kids, friends, book club, or the person behind you in the coffee line. Scams flourish in silence and shame. Talking honestly is one of our strongest protections. In retirement, urgency belongs in spin class. Not your inbox. What to Do If You Took the Bait No judgment here. These scams are truly sophisticated. Smart, experienced, financially educated people fall for them, as we've just established. If you think you've been scammed, stop engaging immediately, change your passwords, contact your bank to flag or freeze your account, run a security scan on your device, and report it to the Canadian Anti-Fraud Centre at 1-888-495-8501. Reporting matters even if you cannot recover the money. It protects the next person in line. Think of it as cutting the line before the fish swims off with your whole tackle box. 3 Things Worth Setting Up This Week to Protect Yourself from Fraud These take 20 minutes and quietly protect you around the clock. Two-factor authentication (2FA) adds a second verification step. It's usually a text code. And it helps ensure that a stolen password alone won't give access to your accounts. Credit Card controls allow you to lock and unlock your debit or credit card instantly through your bank's app, so if something seems suspicious, you can freeze it within seconds. Real-time alerts enable you to set notifications for any transaction over a threshold you specify, so if someone is spending your money, you are informed immediately, rather than finding out at the end of the month when the damage is already done. Don't Get Hooked by Fraud. Retirement should be about freedom. The freedom to fish from a proper dock, travel somewhere warm, and spend your money on things that truly bring you happiness. It's not meant to involve fake urgency, suspicious links, or people who want your SIN and the name of your childhood cat. We Need to Do More to Protect Seniors The fraud prevention system in this country, to be frank, hasn't kept pace with the rise of fraud itself. That gap is real, it's growing, and it needs more attention than it currently gets. Meanwhile, the best we can do is stay informed, keep in touch with trusted people, and not let embarrassment prevent us from seeking help or reporting what happened. You worked hard for what you have. You deserve to enjoy it without looking over your shoulder. So enjoy the lake. Take the cruise — a real one that you booked yourself. Spend wisely, live well, and protect what's yours. And if anyone ever tells you that you've won something you never entered? Smile. Wish them a Happy April Fool's. Then hang up. Have a scam story, a close call, or thoughts on what fraud prevention is getting right or getting wrong? I would love to hear from you. Drop it in the comments or send me a note. This is exactly the kind of conversation we should all be having, and the more real experiences we share, the better equipped we all are to protect each other. Sue Don't Retire…ReWire! My Book is Now Available for Pre-Order If this message speaks to you, or to someone you love, I hope you will pre-order a copy of Your Retirement Reset. Available September 8, 2026. Here's the link. And if you love supporting Canadian booksellers, please also check with your local independent bookstore. Most can easily order it for you.
When individuals sign up for direct-to-consumer genetic testing, the extent to which they ever think about their genetic data is likely in the context of the service for which they paid: information on predisposition to a genetic illness, or confirmation of an ethnic background, for example. But that data doesn’t just sit on a shelf, and while the most mainstream concern for such services is the privacy of your data, there is also the question of what else the companies do with it, and how. Ana Santos Rutschman, SJD, LLM, professor and faculty director of the Health Innovation Lab at Villanova University Charles Widger School of Law, is particularly interested in the latter. In June 2025, she co-authored an amicus brief centered on data protection and patient’s interests amid genetic testing company 23andMe’s bankruptcy proceedings. In December, many of those same co-authors published a paper in Nature Genetics, highlighting 23andMe’s bankruptcy as “an inflection point for the direct-to-consumer genetics market,” especially as it pertains to the broader corporate use of individuals’ scientific data. The reason? “How that data is used all depends on the policies of the individual companies,” she said. Genetic Testing Companies Use Your Data For More Than The Services You Pay For Those who utilize genetic testing companies—for any reason—are likely also consenting, often unknowingly, to other unrelated items. This includes acknowledgment of information related to how your data might be further used or monetized. “Most people don't think about secondary and tertiary uses of their data,” said Professor Rutschman. “[What they consent to] is displayed on the website somewhere, but it’s not easily understandable and accessible. It’s fine print.” Such companies often operate beyond the traditional “fee for a service” relationship with consumers. Yes, they will give you the information you paid for—finding out whether you have German ancestry or are predisposed to certain genetic disease—but instead of that genetic data just being stored somewhere, it’s often sold for research purposes. Today, in the age of AI big data, that might look something like this: The company puts your data in a box with parameters, along with thousands of others. Perhaps they are then able to observe a pattern that, until all that data was compiled, was previously unknown. They come up with a diagnostic or a medicine and patent it. That patent is licensed to somebody else, and the company makes money on the product. The use of that data for scientific purposes—even ones that turn a profit— is not problematic in itself, says Professor Rutschman. “Some people may even choose a company that allows scientific research over one that doesn’t. Many people may not care, but some will. The uses are not common knowledge, and that is worrisome. The public should be well-informed about what’s happening.” Deeper problems may arise when they aren’t informed of those potential uses of their data. Professor Rutschman cited the infamous Henrietta Lacks case, in which Lacks’ cells were, and continue to be, one of the most valuable cell lines in cancer research. Neither Lacks nor her family were paid for the widespread use of her genetic material until a settlement was reached long after her death. “When you have biologics involved, a concern is that if you have something potentially valuable, you may not see any money from it.” Bankruptcy Can Cause Policy Upheaval To understand the role bankruptcy can play in all of this, one needs to refer back to the power of individual company policy in this space. There are no external laws that dictate how these companies can further monetize their data, says Professor Rutschman, as long as they don’t violate other laws, such as privacy laws. That means that when a company like 23andMe goes bankrupt, as was the case in 2025, new ownership could enact completely different corporate policies for use of their property. In their specific case, the company was essentially bought back by 23andMe founder and CEO Anne Wojcicki’s non-profit, all but ensuring policies would remain the same. But that is exactly why Professor Rutschman and others are highlighting this specific case. “Bankruptcy is bad in the sense that there's a lot of uncertainty,” she said. “In this instance, the person coming in was the person who was there before, so the policy is likely to continue. But that's very rare. There are a roster of companies with access to biological materials. 23andMe is a good example of something not going horribly wrong, but with the understanding that it absolutely could.” Ways in which that could happen could be new ownership undermining the original intent of the data use by cessation of the company’s previous policies, or charging exorbitant prices to other entities to use that data for scientific research. “Because there is no law, these new owners can essentially do as they please with their proprietary data, unless they do something incredibly careless that amounts to the level of illegal,” Professor Rutschman said. “And that is concerning.” Onus Falls to Companies to Enact Safeguards To ensure a worst-case scenario for such companies does not unfold in a bankruptcy situation, Professor Rutschman points to a number of safeguards they could enact to protect their original commitments, ensure equitable access to data for scientific research and promote fair trade. One of which is implementing a company policy stating that commitments from a previous iteration of the company need to be honored if ownership is transferred. Those could include, as the authors recommend, policies “honoring original research-oriented commitments under which the data were collected,” as well as not “enclosing the dataset for exclusive commercial use.” She also highlights the need for Fair, Reasonable, and Non-Discriminatory (FRAND) voluntary licensing commitments, which are inherently more science and market friendly. “Companies in many sectors have committed to this approach, and we are saying it should apply in this space as well. You’ll charge your royalty, but it can’t be a billion dollars for a data set, nor would it be done by exclusively selling to one entity. You can get that billion dollars by selling to 15, 50 or 100 companies, and from a scientific research perspective, that’s what we want. Otherwise, you have a monopoly or duopoly. “There are a lot of different models that can be used, but ultimately what we are arguing is leaving this unaddressed is a really bad idea. It leaves everything exposed, and something bad is more likely to happen.”

Carney Cares. The Tax Code Doesn’t.
Retirement analyst and author Sue Pimento looks more closely at the just-announced "Canada Groceries & Essentials Benefit Program" in the broader context of the country's overall tax-and-benefit system. A closer analysis of steep GIS clawbacks layered on top of taxes shows that some seniors face tax rates comparable to those of the country's highest earners. Pimento argues that we should address this “participation tax” to ensure seniors earn more without being penalized for their work. Prime Minister Mark Carney just announced the Canada Groceries and Essentials Benefit. The intent is good. The relief is welcome. The tax code, however, did not get the memo. Important Disclaimer (Please Read) This article is for educational and discussion purposes only and does not constitute financial or tax advice. Canada's tax and benefit system is complex, highly individualized, and subject to frequent changes. Before making any financial or tax decisions, consult a qualified professional familiar with seniors' benefits, including GIS, OAS, CPP, and related clawbacks. Now that we've cleared that up, let's talk… Here’s a quick overview of what was announced. What the Canada Groceries & Essentials Benefit Program Covers Bigger Benefit Cheques: About 12 million Canadians will receive relief. Food Bank Relief: $20 million to food banks through the Local Food Infrastructure Fund. Food Supply: Immediate expensing for greenhouse buildings to bolster domestic production. Food Security: A national strategy including unit price labelling and enforcement by the Competition Bureau. Business Support: $500 million in supply chain support to help businesses absorb costs rather than passing them on to consumers. These ideas aren’t bad. Some are very sensible. Taken together, the Government estimates in its announcement that these measures would "provide up to an additional $402 to a single individual without children, $527 to a couple, and $805 to a couple with two children. They go on to say that at these levels, Canada’s new government will be offsetting grocery cost increases beyond overall inflation since the pandemic." On paper, this looks helpful. Unfortunately, paper has never had to buy groceries. But… You knew there was a “but” coming. Government announcements are legally required to include one. A Little-Known Tax Reality That Makes You Shake Your Head New research shows Canada's tax-and-benefit system disadvantages low-income seniors who work. The issue? It's hidden in the tax code. On January 28, 2026, a Zoomer Radio Fight Back discussion hosted by Libby Znaimer highlighted the issue. Guests included: • Gabriel Giguère, Senior Policy Analyst, Montreal Economic Institute • Jamie Golombek, Managing Director, Tax & Estate Planning, CIBC Financial Planning & Advice Their conclusion? Canada's tax system discourages low-income seniors from working exactly when they need income the most. Many seniors discover (usually the hard way) that a small side hustle doesn't always pay off. It can lead to higher taxes and benefit clawbacks. Work a little more, and Ottawa takes a lot more. Why Seniors Are Still Working Because the math doesn't add up. Either way. More than 600,000 older adults live below the poverty line. Meanwhile, rent, food, utilities, insurance, and property taxes are increasing faster than pensions ever did. More seniors are employed, particularly GIS recipients. MEI analysis indicates that GIS recipients with work income increased by 56% from 2014 to 2022, rising to 64% among those aged 65–69. These seniors aren't working for "fun money." They're working to keep the lights on and purchase medication. Reviewing the details reminded me of a long-standing issue in my research on income and cash flow for Canadians aged 55 and over. Many Canadians can’t make ends meet and are forced to work well past 65. Yet Canada’s tax system punishes low-income seniors for working—exactly when they need income most. To understand why, we need to look at the Guaranteed Income Supplement. The Guaranteed Income Supplement (GIS) Program for Low-Income Seniors Here's how the GIS benefits work: • A non-taxable monthly benefit on top of Old Age Security for low-income seniors. • Roughly one-third of OAS recipients also receive GIS—over 2 million Canadians. • For a single senior with no other income, the maximum annual benefit is about $13,000. (Source: Government of Canada GIS website) The program has done meaningful work. Combined with OAS, CPP, and private pensions, Canada dramatically reduced senior poverty over the past half-century. But there’s a catch hiding in the design. Think of GIS as a hug that tightens when you try to stand up. The GIS Clawback Problem for Canadians GIS recipients can earn only $5,000 per year in employment income before clawbacks begin. After that, GIS takes back 50 cents of every dollar earned—before income tax and payroll deductions. A partial exemption applies to the next $10,000, where 25–37.5% is clawed back. The program helps seniors—right up until they try to help themselves. How the GIS Clawback Works Against Working Seniors Let me illustrate this. Meet Agnes. She is about to learn more about marginal tax rates than any bookstore employee should. Agnes is between 65 and 69 years old, lives alone, and receives OAS and CPP. Rising costs push her to take a job at a local used bookstore. She works about 15 hours a week at roughly minimum wage. Here annual gross employment income is about $13,000 Here’s what happens: • Her employment income triggers GIS clawbacks once she exceeds $5,000. • She pays income tax, CPP contributions, and sometimes EI premiums. • Between taxes and clawbacks, much of her earnings disappear. Simple version: Agnes works more hours but keeps far less than expected. When you keep 20 cents on the dollar, even capitalism looks confused. Agnes didn’t go back to work for the thrill of alphabetizing mystery novels. She did it to afford her prescriptions. A Canadian Tax System That Punishes the Wrong Thing If we’re going to test income, test investment income. Fine. Tax it. But employment income? Showing up? Working? The system treats that like misconduct. Once you add income tax, CPP contributions, and the loss of other credits, low-income seniors can face effective marginal tax rates of 70–80% on modest earnings. Nothing says “fairness” like taxing a bookstore clerk harder than a boardroom executive. As Gabriel Giguère of the Montreal Economic Institute has noted, "this level of taxation normally applies to wealthy Canadians—not seniors living in poverty." In a well-researched economic brief, Giguère and Jason Dean, Assistant Professor of Economics at King’s University College at Western Ontario, present a compelling argument for policy change. This comment by Giguère and Dean nicely sums up their key findings: "For various reasons, including insufficient pensions to maintain their living standards, seniors are increasingly turning to work. Yet the current tax-and-benefit system merits reform as it undermines their efforts, with the harshest effect on low-income seniors." One-Time Credits Don’t Fix Structural Problems At Davos, Mark Carney famously said, “Nostalgia is not a strategy.” Fair point. So why does our benefit system still behave as if retirement lasts ten years and ends with a gold watch? The system still thinks retirement lasts ten years and includes a gold watch. People are living longer. Many will spend 25 to 30 years in retirement. Some want to work. Many need to. A grocery credit helps. But a broken incentive structure still breaks people. Common Sense Tax Solutions the Canadian Government Should Consider 1. Raise the GIS earnings exemption The Montreal Economic Institute recommends raising it to around $30,000. Estimated cost: $544 million annually. Modest relative to the program’s size. 2. Exempt employment income from GIS clawbacks (at least partially) Keep testing investment income. Stop penalizing work. 3. Rethink retirement assumptions Policy built around “retire at 65 and earn almost nothing” no longer matches reality. None of these ideas are radical. They’re just… current. What to Ask Your Accountant About Your Tax Rate Get professional advice. Not generic advice. Not from Google. Not from your unemployed nephew. Ask specifically about: • Pension income splitting • Strategic RRSP contributions • Consulting or corporate structures where appropriate • Creative but compliant barter arrangements • CPP and OAS deferral strategies • Documentation. Lots of documentation. When clawbacks are involved, paperwork is your lifeboat. A Short, Honest Take Grocery relief is appreciated. The intent is good. But until Canada fixes a tax system that punishes low-income seniors for working, affordability will remain fragile. This isn’t about blame. It’s about aligning incentives with reality. Right now, it feels like we’re helping seniors swim by handing them bigger life jackets—while quietly drilling holes in the boat. And yes… I need to lie down. I feel another blog coming on. Apparently, exercising this much common sense counts as cardio. Sue Don't Retire...Re-Wire! Want more of this? Subscribe for weekly doses of retirement reality—no golf-cart clichés, no sunset stock photos, just straight talk about staying Hip, Fit & Financially Free.