Experts Matter. Find Yours.
Search experts on 50,000+ topics. Or browse by topic category.
- Recent Searches
Featured
Global experts with a broad range of areas of expertise.



Patrick Markey, PhD
- Title
- Professor of Psychological and Brain Sciences | College of Liberal Arts and Sciences
- Role
- Villanova University
- Expertise

Jagdish N. Sheth
- Title
- Charles H. Kellstadt Chair Emeritus of Marketing
- Role
- Emory University, Goizueta Business School
- Expertise


Allison Stock, PhD
- Title
- Senior Vice President, Environmental, Health & Safety
- Role
- J.S. Held LLC
- Expertise


Connecting credible expert sources & academic research
ExpertFile is a trusted resource for journalists, industry, funding agencies and government policymakers looking for fresh perspectives and innovative academic research.


Spotlights
Read expert insights on a wide variety of topics and current events.
When Diesel Prices Surge, What Happens to the Supply Chain?
Diesel rarely gets the same public attention as gasoline, but its price can reverberate across almost every part of the economy. Global diesel prices have climbed to record levels amid significant supply disruptions, putting additional pressure on trucking, agriculture, manufacturing and the movement of goods. The impact is raising an important question for businesses: When does a fuel-price spike become a genuine supply-chain problem? Dr. Chris Caplice, founder and director of the MIT FreightLab at the MIT Center for Transportation and Logistics, says the freight industry has spent decades developing mechanisms to manage fuel volatility. But that doesn't mean every carrier experiences the impact equally. “Smaller carriers not only have older equipment and are not getting fully reimbursed, they also have cash flow challenges.” Caplice notes that fuel surcharge programs help shippers and carriers share the risk of changing diesel prices. However, carriers must pay for fuel immediately while surcharge payments can arrive 30 days or more later — creating particular pressure for smaller operators. Dr. Chris Caplice serves as the Executive Director of the Massachusetts Institute of Technology’s Center for Transportation & Logistics (CTL) where he is responsible for the planning and management of the research, education, and corporate outreach programs for the center. View his profile The consequences can extend well beyond the trucking company. According to Caplice, every 20-cent-per-gallon increase in diesel costs a shipper approximately three to four cents per mile. Rather than immediately redesigning supply chains, companies are more likely to look for operational efficiencies, including increasing truck utilization or shifting freight to intermodal transportation where practical. So, what should businesses be watching? Small-carrier vulnerability: Sustained fuel costs could create significant cash-flow pressure and contribute to some smaller trucking companies exiting the market. More efficient freight: Companies may increasingly focus on fuller loads, better utilization and other measures that reduce unnecessary miles. Intermodal opportunities: Higher trucking costs could make shifting appropriate freight between truck and rail more attractive. Electric trucks: Persistently expensive diesel could strengthen the economic case for electric Class 8 trucks in some applications. The six-month question: Caplice suggests duration matters. If elevated diesel prices persist for six months, businesses may have greater reason to view the situation as something more significant than temporary volatility. The broader freight network has considerable capacity to adapt, Caplice says. But the longer high diesel prices persist, the more important efficiency, carrier stability and transportation strategy become for companies trying to manage costs and maintain resilient supply chains. Dr. Chris Caplice is founder and co-director of the MIT FreightLab and Executive Director of the MIT Center for Transportation & Logistics. His research focuses on freight transportation, procurement, planning, performance and infrastructure. If you’re interested in speaking with Dr. Caplice about rising diesel prices, freight transportation and what sustained fuel costs could mean for supply chains, simply click on his profile below to arrange an interview today.
When Food Supply Chains Break: Why Traceability Matters
A foodborne illness outbreak can begin with a single contaminated product. Finding where that contamination occurred, however, can mean tracing a product backward through a complicated network of retailers, distributors, brokers, carriers, wholesalers and suppliers. That challenge has been brought into focus by the 2026 Cyclospora outbreak, which has disproportionately affected lettuce and resulted in thousands of confirmed cases and thousands more under investigation in the United States. Dr. Christopher Mejía Argueta, a Research Scientist at the MIT Center for Transportation and Logistics, compares tracing the source of a foodborne illness outbreak to a “criminal investigation. “After officials investigate that, they go back and identify where the retailers sold those potential products, and then they start going upstream in the supply chain.” The process starts with consumers who have been diagnosed and works backward through the supply chain, identifying where products were sold before moving upstream through distributors and brokers and ultimately toward suppliers and vendors. But the more complicated the supply chain becomes, the harder that investigation can be. “The more the complexity grows, the more difficult it is to identify where all of this happened.” Chris Mejía Argueta is a Senior Research Scientist at the MIT Center for Transportation and Logistics with 20 years of experience delivering applied research in 20+ countries. His work helps organizations turn complex supply chain challenges into practical strategies that improve competitiveness, efficiency, and flexibility. View his profile Mejía Argueta explains that contamination could potentially occur at several points, including at the carrier or wholesale level. With fresh produce often moving through numerous intermediaries before reaching consumers, each additional participant can add another layer to the investigation. Once a likely source is identified, recalls become an important tool for containing the outbreak. Potentially contaminated products must be located, brought back and destroyed, while supply chain stakeholders also need to consider the possibility of cross-contamination involving other products that came into contact with them. The 2026 Cyclospora outbreak raises broader questions about how food supply chains can improve visibility and traceability as they become increasingly complex. How can better traceability help investigators identify the source of contaminated food faster? What happens when products move through numerous distributors, brokers and carriers? Where can contamination occur as food moves through the supply chain? How do recalls work once a potentially contaminated product has been identified? What role does supply chain visibility play in limiting cross-contamination? How can food supply chains become better prepared to identify and contain future outbreaks? If you’re interested in speaking with Dr. Mejía Argueta about food supply chain traceability, the challenges of tracking contamination and what the 2026 Cyclospora outbreak reveals about supply chain visibility, simply click on his profile below to arrange an interview today.
Got Expertise to Share?
ExpertFile works with leading organizations with trusted experts. We help make their expertise more discoverable, structured, and actionable for AI-driven discovery, strategic outreach, and real-world opportunities.
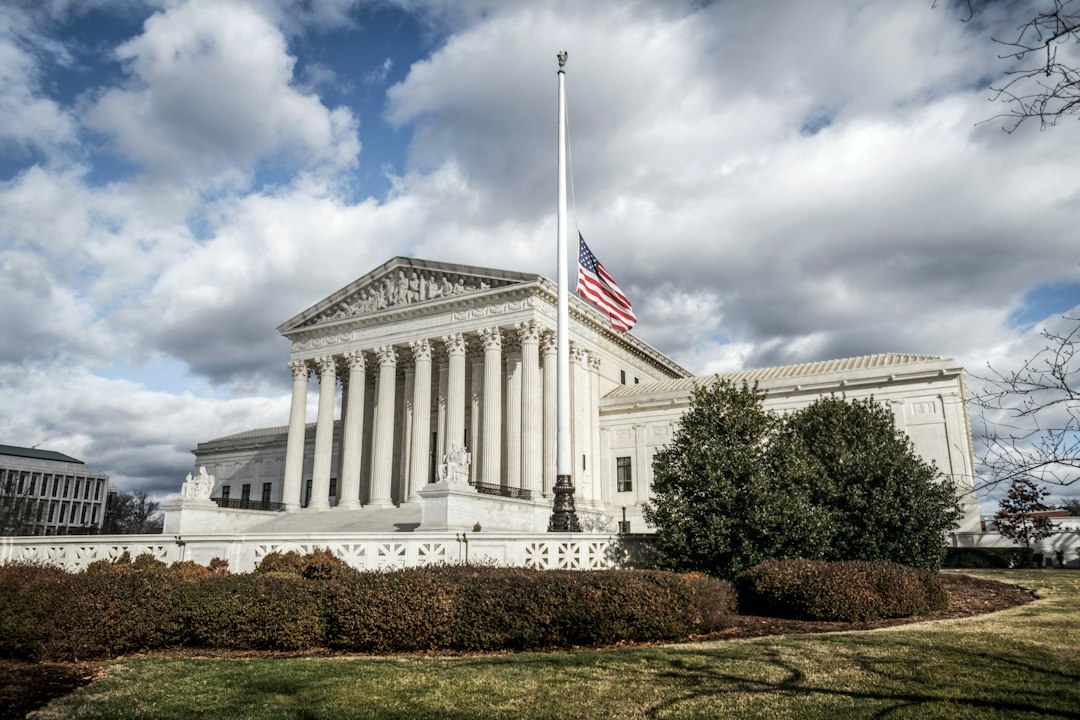
Supreme Court Expansion Debate Raises Questions About Judicial Independence
Should the Supreme Court remain at nine justices, or would a larger bench strengthen the nation’s highest court? That question is drawing renewed attention after a Republican-backed constitutional amendment to permanently limit the court to nine seats failed in the House in September. Democratic proposals include expanding the court to 13 justices, while supporters and opponents disagree over whether changing its size would improve its credibility or deepen political divisions. Although nine justices may seem like a constitutional requirement, Congress determines the court’s size. Its membership changed several times before settling at nine in 1869. Legislation introduced by Rep. Al Green would increase that number to 13, reopening a debate over how much influence elected officials should have over the structure of the judiciary. Supporters see expansion as a way to restore balance and bring additional perspectives to the bench. Critics worry that adding seats to secure favorable rulings could encourage future majorities to pursue similar changes. The broader issue is how to preserve public confidence in an institution designed to exercise independent judgment. The Constitution’s protections for federal judges, including service during good behavior and protection against salary reductions, are intended to shield them from partisan pressure. Changing the court’s membership would create new opportunities for presidential appointments, with consequences that could extend well beyond a single administration. As the debate continues, Americans face a consequential question: What reforms would strengthen accountability while preserving the Supreme Court’s ability to interpret the law independently?


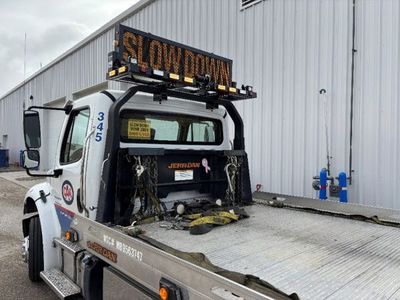
Ahead of National Slow Down Move Over (SDMO) Day, acknowledged on October 17, CAA Manitoba is calling for regulatory changes that would allow tow trucks to use vehicle-mounted electronic warning signs, known as Variable Message Signs (VMS), to give approaching drivers an earlier warning of roadside incidents. Every day, tow truck operators work alongside live traffic to help stranded motorists, but many drivers still do not give them the same space and protection they provide emergency vehicles such as police, fire and ambulances. "For tow operators and first responders, the roadside is their workplace," said Teresa Di Felice, assistant vice president, government and community relations, CAA Manitoba. "Slowing down and moving over is a simple action drivers can take to make a meaningful difference to protect the people who assist Manitobans every day." Variable Message Signs (VMS) provide drivers with advance warning of roadside incidents, giving them more time to react safely. The technology is already authorized in over 40 U.S. states, as well as in Australia and across the European Union. Research from the AAA Foundation for Traffic Safety found drivers were more likely to slow down and move over when a VMS was active, with the odds of a vehicle moving over increasing by 95 per cent. CAA Manitoba continues to discuss the use of truck-mounted VMS technology with government and industry stakeholders as part of broader efforts to improve roadside safety. A pilot project underway in Ontario is testing how the technology can help protect roadside workers, including tow operators. Despite growing awareness of SDMO laws, compliance around tow trucks continues to lag behind other emergency vehicles. CAA research found members were less likely to move over for tow trucks than for police, ambulances or fire trucks. Among those who did not move over for a tow truck, nearly half said they did not know it was required by law. "Tow truck operators are often among the first people to arrive when someone needs help," says Di Felice. "They deserve the same care and protection we give other emergency responders." To help address the issue, CAA has launched a new public service announcement that puts motorists in the shoes of the roadside workers who assist drivers every day. Rather than focusing solely on the rules of the road, the campaign highlights the people those rules are designed to protect. Watch the PSA here. CAA research also found that while eight in 10 members understand the core Slow Down, Move Over message, some remain unclear about the exact action required when approaching a roadside incident. The campaign aims to close that gap through education and awareness. To learn more about SDMO laws, please visit: https://www.caamanitoba.com/SDMO

All this talk lately about Trump and Carney squaring off has made me reflect on matters closer to home. My living room has never quite reached the level of a televised leaders’ debate, but retirement has a way of turning minor domestic disagreements into full parliamentary sessions. And unlike politicians, you can’t call a recess and fly to Florida. For years, we’ve been sold a lovely picture of retirement. The alarm clock disappears. The kids have finally stopped treating your house like a storage locker. There are leisurely breakfasts, travel, golf, grandchildren, and coffee on the patio on a Tuesday morning simply because you can. And there is your spouse. Every. Single. Day. For many couples, this is wonderful. Even in the happiest relationships, though, somewhere around the third consecutive Tuesday morning together, a thought may quietly surface: Have you always chewed like that? We spend years trying to figure out whether we have enough money to retire. We calculate pensions, RRSPs, CPP, home equity, and how long our savings might last. We consult financial planners and make budgets. Some of us even build colour-coded spreadsheets, which I think is taking things a little far (just saying). Far fewer couples spend time figuring out how they will retire together, and that’s a different calculation altogether. Two Retirement Plans before One During our working years, most couples have something that retirement quietly removes: separation. You go to work. I go to work. You have your colleagues, routines, frustrations, and responsibilities, and I have mine. We leave each other in the morning, collect a day’s worth of stories, and come home with something to talk about. Retirement can fold two fairly independent lives into the same house and the same calendar, usually by the first Monday. Research backs this up. A German study of 2,117 couples, drawing on more than 30 years of national survey data, found that on average both partners grew more satisfied with life around retirement. The changes were also highly correlated within couples, so when one partner’s satisfaction slipped, the other’s tended to slip right along with it (Weber et al., 2021). Your retirement becomes my retirement, whether I applied for the position or not. Then come the expectations. One person has been dreaming of travelling for 20 years. The other would happily never set foot in an airport again. One wants to move, and one wants to stay. One wants to golf four days a week. The other thought retirement meant finally doing things together. One wants to help the kids financially. The other believes the kids are 43 and it may be time they gave adulthood a whirl. Even the timing can cause friction. One of you retires in June, the other has three years left before the pension kicks in, and suddenly someone is home all day reorganizing the spice drawer. Research on how couples make retirement decisions suggests that the way the call gets made, and whether both people feel they had a say, shapes how satisfied they are with retirement afterward (Szinovacz & Davey, 2005). The relationship you bring into retirement also comes along for the ride. Old patterns of closeness and conflict travel with you like carry-on luggage, and retirement simply changes the scenery around them (Davey & Szinovacz, 2004). That makes me wonder whether every couple needs two retirement plans before they have one. What does your retirement look like? What does mine look like? Where do they overlap? Those questions may matter more than whether we can afford the Viking cruise. And Then There’s Money Of course there is. Money has always had an extraordinary ability to walk into a perfectly pleasant conversation and leave with a baseball bat. In retirement it gets even more emotionally charged, because our financial psychology shifts. During our working years, another paycheque is always coming. In retirement, many of us start drawing down assets we spent decades building, which can feel completely sensible to one spouse and mildly terrifying to the other. This is where FORO, Fear of Running Out, can pull up a chair at breakfast. One partner sees $800,000 as security. The other sees the same $800,000 as a number that can only get smaller. Suddenly a $12,000 trip to Italy is carrying a lot of luggage: safety, control, mortality, and whether 93-year-old you might someday need that money. Then health can change the equation again. A spouse gets sick. Mobility changes. One person becomes a caregiver, and independence starts to slip away. Retirement plans that once looked beautifully aligned suddenly don’t, and that is a lot of change for any relationship to absorb. Apparently, Fighting Isn’t Necessarily Bad Three very different thinkers have helped me rethink the whole subject: an ancient Chinese general, a modern conflict facilitator, and a psychologist with a lab full of arguing couples. Sun Tzu’s The Art of War is about military strategy, yet one of its most enduring ideas travels surprisingly well into marriage: understand the situation, understand the other person, and don’t waste resources on battles that don’t need to be fought. Priya Parker comes at conflict from almost the opposite direction in her new book, The Art of Fighting (2026). Her work explores how conflict can strengthen relationships when people engage with it well. She calls this idea “healthy heat.” Some difficult conversations need enough heat to burn through to what actually matters. Then there is psychologist John Gottman, who studied couples over time and found something I love: happy couples don’t all fight the same way (Gottman, 1993). His research identified three stable types. Validators calmly talk their disagreements through. Avoiders would much prefer to change the subject. Volatile couples argue loudly and passionately and keep their marriages intact anyway. The couples headed for trouble were the hostile ones, along with the ones who had quietly checked out. So you and I don’t have to argue like the nice couple down the street. They look exhausted and boring, to be frank. What seems to matter is whether we can disagree and still hold on to respect, affection, and the sense that we are on the same side. That calls for something to sit beside the retirement financial plan. The Retirement Rules of Engagement 1. Figure out what you’re really fighting about. Before digging in your heels, ask why this matters so much to each of you. The argument about selling the house may really be about losing independence. A fight over spending can be tangled up with FORO. Too much golf might be about purpose for one person and loneliness for the other. And the argument about money may have very little to do with the actual numbers. Once the real issue is on the table, at least you’re having the right argument. 2. Choose your battles. Sun Tzu would make an excellent retirement consultant. Some things matter enormously, and others really don’t. If your spouse has loaded the dishwasher incorrectly for 37 years and everyone is still alive, victory may no longer be strategically important. 3. Keep the heat healthy. Disagreement has a place in a strong relationship. Parker’s idea of healthy heat gives us permission to have uncomfortable conversations without treating the discomfort as proof that the relationship is in trouble. Say the difficult thing. Ask the awkward question. Then stay curious about the answer. 4. Remember who is sitting across from you. This is the person you chose to build a life with. Opposing counsel bills by the hour. Gottman’s research is especially useful here, because hostility and emotional disengagement are the real warning signs. Anger passes. Contempt has a nasty habit of moving into the spare room. 5. Build some mine, yours, and ours. Two people don’t need to become one organism to have a good retirement. Separate interests, friendships, and activities give each partner purpose and independence, plus fresh material for dinner conversation. Then build the shared things on purpose too: travel, grandchildren, exercise, volunteering, cottage time, date nights, or whatever makes retirement feel like ours. A little absence can still make the heart grow fonder. 6. Know when you’re stuck. If you keep having the same argument, if conversations regularly turn hostile or contemptuous, or if one of you has simply stopped engaging, outside help may be worth it. A couples therapist can untangle relationship patterns. A financial planner can put real numbers around money fears. A retirement coach can help when identity and purpose are causing friction. Sometimes the most useful person at the kitchen table is the third one. What About Grey Divorce? Grey divorce is worth a few minutes here, because ending a marriage later in life is especially hard to recover from financially, and it ripples through the whole family, right down to the grandchildren who now spend Christmas in two places. The Canadian story, however, is less dramatic than the headlines suggest, partly because so many of those headlines are American. In the United States, adults 50 and older made up 8% of all divorces in 1990 and nearly 40% in the latest figures, and their divorce rate doubled between 1990 and 2010 before levelling off (Westrick-Payne & Brown, 2024). Canada never had that boom. Statistics Canada reports that the divorce rate among Canadians aged 50 and older rose 26% between 1991 and 2006, from 4.2 to 5.3 divorces per 1,000 married people, and has since remained relatively stable (Statistics Canada, 2022). Grey divorce remains considerably less common here than divorce among younger adults, so if you’ve read that it has doubled, you were reading about Americans. Still, divorce at 65 is financially different from divorce at 35. There are fewer working years to rebuild. One household becomes two. Housing, retirement income, pensions, estate plans, and family relationships can all take a hit, and women tend to feel it most. A Statistics Canada study that tracked Canadians from their mid-50s into their 70s found that divorced women kept about 70% of their family income, compared with about 87% for women who stayed married (Mehdi, 2023). The study concluded that divorce lowers living standards in retirement more than the death of a spouse does. Till Death Do Us Part Is Longer Than It Used to Be A couple retiring in their 60s could easily have another 20 or 30 years together. That’s an extraordinary gift. It’s also a very long time to argue over the thermostat. Our health will change, our finances may shift, and our interests will wander off in directions neither of us saw coming. The people we were when we walked away from our careers won’t necessarily be the people we are at 75, 80, or 90, so our relationships need room to grow with us. So pick the battles worth fighting, bring a little healthy heat to the ones that matter, and concede the rest, especially the dishwasher. Thirty years of retirement works out to more than 1,500 Tuesdays together. It would be a shame to spend them arguing about the forks. Don’t retire. ReWire. Sue P.S. Retiring solo? Don’t get too comfortable. Many of the same issues show up with adult children, friends, and family, along with everyone’s sudden assumption that you now have all kinds of free time. I’ll tackle that one in two weeks. My Book is Available for Order: I hope you will consider ordering a copy of Your Retirement Reset for yourself, a friend, or someone you love. Published by ECW Press and is available through Indigo or Amazon and McNally Robinson. If you like supporting Canadian booksellers, check with your local independent bookstore too. Most can order it.

$787 a Month for a New Car? The Growing Cost of Getting Behind the Wheel
Buying a new car is becoming an increasingly expensive proposition for American consumers, with monthly loan payments now averaging a staggering $787. According to a recent DC News Now report, the average new-car loan is approaching $45,000, raising concerns about affordability, household debt and the long-term financial commitments consumers are making just to get behind the wheel. And the monthly loan payment is only part of the equation. Insurance premiums, maintenance, fuel and other ownership expenses can push the actual cost of driving considerably higher. For consumers already managing rising household expenses, the decision to purchase a vehicle has become increasingly complicated. Beyond the Sticker Price: What Consumers Need to Know Dr. Kashef Majid, Associate Professor of Marketing at the University of Mary Washington, has studied how consumers value hybrid and electric vehicles, including the financial and environmental motivations behind purchasing decisions. He was also named one of the 50 Best Undergraduate Business Professors of 2024 by Poets & Quants. View his profile Majid has also shared his expertise with WalletHub, offering first-pen perspective on car insurance costs, pricing fairness and the importance of making informed decisions when shopping for coverage. His insights are particularly relevant as Americans face record-high car payments, with insurance premiums adding another significant expense to the overall cost of vehicle ownership. As consumers grapple with rising costs, Majid can help explain what's driving vehicle affordability challenges, how purchasing decisions are changing and what motorists should consider before taking on substantial financial commitments. If you're interested in speaking with Dr. Kashef Majid about rising car payments, vehicle affordability, insurance costs and consumer behavior, simply click on his profile below to arrange an interview today.

Inflation and Interest Rates Put Household Budgets and Business Plans Under Pressure
For American families, inflation is felt in everyday decisions: what to buy at the grocery store, how much to spend on gas and whether a major purchase can wait. This week’s Consumer Price Index report will bring those pressures into focus as the Federal Reserve considers its next interest-rate decision. Some officials have signaled that another increase could wait until December, but stronger inflation data could strengthen the case for action at the October 27–28 meeting. The stakes extend beyond the price of everyday necessities. Higher interest rates can make credit card balances and new auto loans more expensive, adding pressure to households already managing rising living costs. Homebuyers also face difficult affordability decisions, with the average 30-year fixed mortgage rate reaching 7.40% last week. Mortgage rates respond to bond markets and inflation expectations as well as monetary policy, meaning uncertainty can affect buyers even before the Fed acts. Businesses face a similar calculation. When financing becomes more expensive, purchasing equipment, expanding operations or hiring additional employees can become harder to justify. Rising operating costs can also force companies to choose between raising prices and accepting smaller profit margins. For policymakers, the challenge is to bring inflation under control while preserving employment and economic growth. This week’s report will offer another signal about that balance—and help shape the financial decisions families and businesses make in the months ahead.


Measles Makes a Dangerous Comeback as Pennsylvania Outbreak Tops 1,000 Cases
Measles was declared eliminated in the United States in 2000. More than 25 years later, the highly contagious disease is making a troubling comeback, with Pennsylvania now confronting an outbreak that has surpassed 1,000 confirmed cases. According to an October 7 update from the Pennsylvania Department of Health, the state has recorded 1,078 confirmed cases across 41 counties, including 207 hospitalizations and five measles-associated deaths. The figures underscore the serious public health consequences of a disease that can largely be prevented through vaccination. The outbreak is also raising important questions about declining vaccination rates, community immunity and whether other states could experience similar outbreaks. Measles spreads through the air when an infected person breathes, coughs or sneezes. The virus can remain infectious in the air for up to two hours after an infected person leaves an area. Early symptoms include fever, coughing, a runny nose and red, watery eyes, followed by a distinctive rash that typically begins on the face and spreads downward. While many people recover, measles can cause serious complications, including pneumonia, brain swelling and, in rare cases, death. Two doses of the measles, mumps and rubella (MMR) vaccine are approximately 97% effective at preventing the disease. Understanding the Outbreak and What Comes Next Dr. Lynn O. Lewis, a Professor of Biological Sciences at the University of Mary Washington, brings extensive expertise in microbiology, virology and infectious diseases. Lewis also directs the university's Irene Piscopo Rodgers School of Science and helped provide scientific guidance during the COVID-19 pandemic. View her profile With measles cases continuing to mount, Lewis can provide valuable perspective on how the virus spreads, why vaccination remains critical and what public health officials can do to contain outbreaks. She is available to help journalists explore several important questions: Why is a disease once eliminated in the United States returning? What makes measles so contagious? How do vaccination gaps contribute to outbreaks? And what lessons from the COVID-19 pandemic can help communities respond more effectively? As Pennsylvania continues its response, the outbreak is a reminder that infectious diseases once considered under control can re-emerge when the conditions that prevented their spread begin to change. If you're interested in speaking with Dr. Lynn Lewis about the Pennsylvania measles outbreak, infectious disease transmission, vaccination and public health preparedness, simply click on her profile below to arrange an interview today.
Slowing Job Growth Raises Questions About the Economy’s Momentum
The U.S. economy added just 29,000 jobs in September, while unemployment edged up to 4.2%, raising concerns about the strength of the labor market. Downward revisions to July and August’s employment figures further weakened the picture, suggesting hiring had been less robust than previously reported. For workers seeking their first job or a new opportunity, the slowdown adds uncertainty to an already challenging economic environment. The report also complicates the Federal Reserve’s next interest-rate decision. Weaker hiring reduced expectations for another rate increase this month, as policymakers weigh inflation concerns against the risk of slowing the economy further. Higher borrowing costs can make business expansion more expensive and discourage spending on homes, vehicles and other major purchases. A softer labor market gives the Fed another reason to consider how much financial pressure households and employers can absorb. September’s figures do not establish that a recession is underway: unemployment has remained between 4.1% and 4.3% since March, and employers are still adding jobs. Nevertheless, the report raises a broader question about whether the economy can sustain growth while hiring remains subdued. The coming months will help reveal whether September represented a temporary slowdown or a more persistent loss of momentum—with consequences for household confidence, business investment and monetary policy.